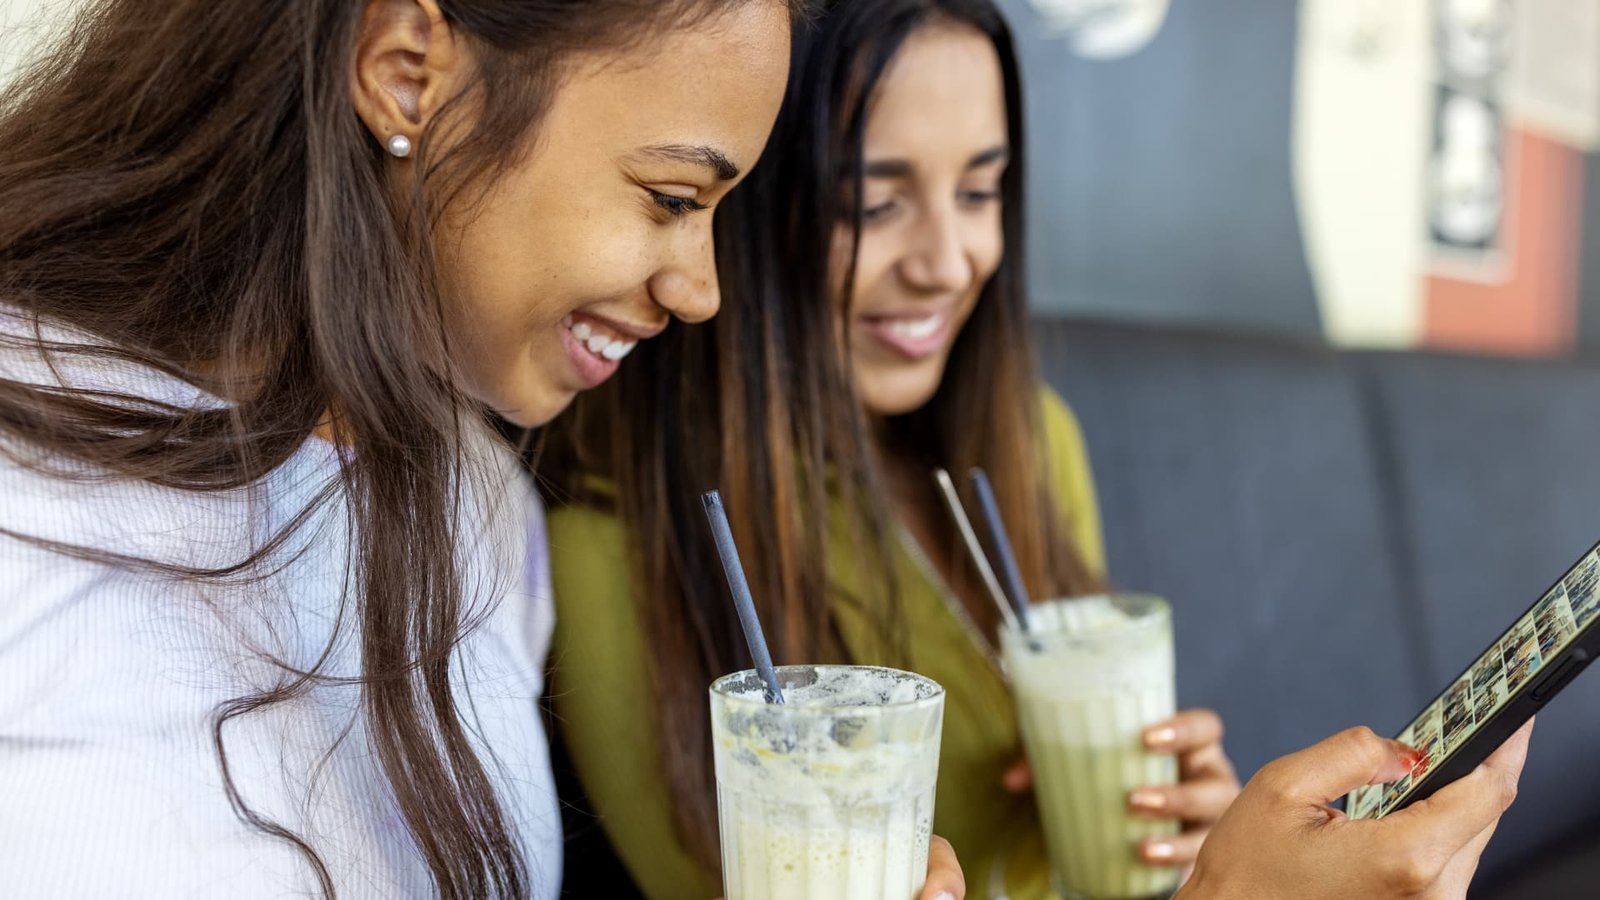
Gen Z may be struggling with larger financial milestones, but that hasn’t stopped them from their daily coffee run.
According to a 2026 Deloitte survey, 55% of Gen Z said financial constraints have delayed a major life decision, like starting a family or continuing their education, because of their current financial situation.
And yet, Gen Z is finding ways to spend on simple pleasures. Ninety-two percent of Gen Zers said they treat themselves to boost their mood on bad days or celebrate good ones, a recent Bank of America study found. Affordable luxury goods (think: your $10 matcha latte with oat milk) often see increased buying during times of financial hardship, a trend commonly referred to as the “lipstick theory.”
Gen Z’s spin on this phenomenon is aptly referred to as the “little treat” economy. Their spending per transaction on both ice cream and baked goods is growing at twice the rate of other generations, and their spending at small and mid-sized coffee shops has increased by over 25% year over year.
While nobody is trying to take Gen Z’s treats away from them, there is a way to indulge responsibly. CNBC Select takes a look at why these little purchases bring so much joy, and some ways you can weave them into your budget without sacrificing too much.
Gen Z’s ‘little treat’ economy
Do you have a credit card or travel rewards question?
Senior reporterJason Stauffercan answer your questions about how to make the most of your credit cards in his weekly Points Pro column. Submit yours here.
Why Gen Z spends on ‘little treats’
To some, splurging on daily rituals like an overpriced chocolate croissant may seem like a frivolous waste of money. But these small luxuries can bring joy in a world where Gen Z is struggling to pay the bills, afford housing and save for retirement.
A recent Federal Reserve report found that, in 2025, almost a quarter (24%) of people ages 18 to 29 — otherwise known as Generation Z — didn’t pay their bills in full in the month prior to the survey. And 47% had help paying everyday expenses from someone outside their household in the prior 12 months, like a cellphone bill, rent or utilities.
When it comes to housing, a separate Bank of America study found almost a third (29%) of Gen Zers said rent or housing costs were the biggest barrier to financial success. They’re also putting more money than recommended toward their rent, or over half of their income (51.9%), according to Experian — well above the 30% guideline.
Gen Z is actually saving for retirement earlier than previous generations, according to the Bank of America study. But they also save the least compared to how much they spend. Perhaps unsurprisingly, a separate KPMG survey found over one-fifth (22%) of Gen Z’s household income is put toward “discretionary” goods and services, the highest of any generation.
It’s clear that Gen Z is struggling financially, but the solution doesn’t have to be all or nothing. While it might take a little time, they can have their cake and eat it too — and still save for retirement.
Build a ‘joy budget’ into your finances
The goal isn’t to be saving every single penny for the rest of your life, but to instead create a system where you feel empowered to make purchases when you want.
If you haven’t already made a budget, you should consider doing so. Smaller, more frequently purchased treats can make it a lot harder to track your overall spending compared to just one or two big-ticket items.
If you’re looking for a beginner-friendly tool, Monarch can be a great place to start. You can bring together your finances, from bank accounts to credit cards, including the value of your home. The app also automatically tracks recurring subscriptions, and you can add a significant other (or roommate), making it easier to save toward a mutual goal or split costs.
Monarch
-
Standout features
Customizable transaction categories, net-worth tracker, investment portfolio tracking, financial forecasting
-
Cost
$8.33/month (billed $99.99 annually); $14.99/month (billed monthly). Get 50% off your first year of Core Plan with code CNBC50
-
Categorizes your expenses
Yes, but users can modify
-
Links to accounts
Automatically syncs with bank accounts, credit cards, loans, retirement plans, investments and more at over 13,000 institutions
-
Availability
Offered for both iOS and Android. Web version also available
-
Security features
Maintaining only read-only access, Monarch utilizes AES 256-bit encryption and multi-factor authentication. It is SOC2 Type 2 certified and syncs accounts via Plaid, MX and Finicity.
Pros
- Seven-day free trial
- Easy-to-navigate dashboard with fully customizable reports and visuals
- Connects with more than 13,000 financial institutions
- Couples or partners can budget together in collaboration mode (each with their own login at no extra cost)
- AI Assistant lets you ask questions about your finances
- Can track property value via Zillow
- Ad-free experience
- Consistent product updates with new features added regularly
Cons
- No free version
- Subscription is more expensive than competitors
- Investment tracking is solid for most users but lacks advanced tools like retirement modeling, fee analysis or Monte Carlo simulations
- Recommendations in the “advice” tab are generic
- No undo feature when reallocating money across budget categories
Building a budget is the first step, but it doesn’t automatically mean you’ll have disposable income. Creating enough financial wiggle room for everyday treats likely won’t happen overnight, but instead through small contributions.
Putting your savings in a high-yield savings account (HYSA) is a great way to make sure the money you’re putting aside is earning you the best return. HYSAs can have APYs of 10X compared to traditional savings accounts. For example, a Live Oak Bank Personal Savings account offers a 4.00% APY and has no minimum balance requirements to open; you can open one with a single penny.
Live Oak Personal High Yield Savings
-
Annual Percentage Yield (APY)
-
Minimum balance
-
Monthly fee
-
Maximum transactions
-
Excessive transactions fee
-
Overdraft fee
-
Offer checking account?
Only a business checking account
-
Offer ATM card?
Pros
- Strong APY
- No minimum deposit and low minimum balance
- No transfer limit
Cons
- No debit or ATM card
- No checking account offered
- No checks for deposits or withdrawals
Spend selectively, not more frequently
If you’re looking to better manage your spending, try to be more selective with how you’re spending your money. Instead of spending on little treats every day, consider saving for more meaningful experiences, like travel or live events.
If traveling is at the top of your list, like the 93% of Gen Zers who planned to travel this past summer, consider a card that not only rewards you for traveling but comes with useful perks for your journeys.
The Chase Sapphire Preferred® Card (see rates and fees) earns a blanket 2X points on all travel purchases (plus 5X points on Chase TravelSM) and a statement credit to cover the Global Entry, TSA PreCheck® or NEXUS application fee. The points you earn can be transferred to 10+ Chase transfer partners, like World of Hyatt or United Airlines, which is one of the most cost-effective ways to travel.
The Chase Sapphire Preferred® Card packs a punch for a $95 annual fee card, offering annual travel credits, comprehensive travel protections, flexible rewards and more.
- You can transfer rewards to all of Chase’s travel partners including World of Hyatt, Southwest Rapid Rewards and many more
- Long list of travel and shopping protections
- Annual Chase Travel hotel credit
- Has an annual fee
- Requires a high credit score
Highlights
Highlights shown here are provided by the issuer and have not been reviewed by CNBC Select’s editorial staff.
- Earn 75,000 bonus points after you spend $5,000 on purchases in the first 3 months from account opening.
- Enjoy benefits such as 5x on travel purchased through Chase TravelSM, 3x on dining, 3x on vacation homes, 3x on gas & EV charging, 3x on top streaming services and online groceries (excluding Walmart, Target, and wholesale clubs), 2x on all other travel purchases, 1x on all other purchases
- Earn up to $100 in statement credits each account anniversary year for hotel stays through Chase Travel
- Count on Trip Cancellation/Interruption Insurance, Auto Rental Collision Damage Waiver,Emergency Evacuation and Transportationand more
- Get a year of complimentary Apple TV when activated by December 31, 2026 – a value of $156.
- Complimentary DashPass which unlocks $0 delivery fees & lower service fees for12 monthswhen you activate by 12/31/27. Plus, a $10 promo each month on non-restaurant orders.
- Receive one statement credit of up to $120 every four years as reimbursement for the application fee charged to your card for a Global Entry, TSA Precheck® or NEXUS application.
- Transfer points to leading airline and hotel loyalty programs
- Member FDIC
Balance transfer fee
Either $5 or 5% of the amount of each transfer, whichever is greater
If you’re more interested in concerts or sports, the Capital One Savor Cash Rewards Credit Card earns 3% cash back on several categories, including entertainment spending. This covers a wide range of options, from aquariums to record stores to sought-after categories like concerts or sporting events.
The Capital One Savor Cash Rewards Credit Card is one of the most rewarding options for earning cash back in categories such as entertainment and dining without paying an annual fee. Plus, you can combine its rewards with Capital One’s travel cards to convert them into transferable miles.
- One of the most rewarding cash back cards for entertainment and streaming services
- No annual fee
- Easy-to-earn welcome bonus
- High APR
- Requires a good to excellent credit score
Highlights
Highlights shown here are provided by the issuer and have not been reviewed by CNBC Select’s editorial staff.
- Earn a one-time $200 cash bonus once you spend $500 on purchases within the first 3 months from account opening
- $0 annual fee and no foreign transaction fees
- Earn unlimited 3% cash back at grocery stores (excluding superstores like Walmart® and Target®), on dining, entertainment and popular streaming services, plus 1% on all other purchases
- Earn 8% cash back on Capital One Entertainment purchases
- Earn unlimited 5% cash back on hotels, vacation rentals and rental cars booked through Capital One Travel
- No rotating categories or sign-ups needed to earn cash rewards; plus cash back won’t expire for the life of the account and there’s no limit to how much you can earn
- 0% intro APR on purchases and balance transfers for 12 months; 18.74% – 28.74% variable APR after that; balance transfer fee applies
- Top rated mobile app
Balance transfer fee
Introductory fee of3%of the amount of each transferred balance that posts to your account during the first 12 months that your account is open. After that,4%of the amount of each transferred balance that posts to your account at a promotional APR that we may offer you at any other time.
We’re not saying you should eliminate your little treats altogether; life gets a lot more dull without them. Instead, being more intentional with your spending and not acting out of habit can help you save and enjoy larger experiences down the road.
Subscribe to the CNBC Select newsletter!
The CNBC Select Recommends newsletter delivers practical money tips each week along with expert-picked financial product recommendations. Sign up here.
Why trust CNBC Select?
At CNBC Select, our mission is to provide our readers with high-quality service journalism and comprehensive consumer advice so they can make informed decisions with their money. Every article is based on rigorous reporting by our team of expert writers and editors. While CNBC Select earns a commission from affiliate partners on many offers and links, we create all our content without input from our commercial team or any outside third parties, and we pride ourselves on our journalistic standards and ethics.
Catch up on CNBC Select’s in-depth coverage ofcredit cards,bankingandmoney, and follow us onTikTok,Facebook,InstagramandXto stay up to date.
Editorial Note: Opinions, analyses, reviews or recommendations expressed in this article are those of the Select editorial staff’s alone, and have not been reviewed, approved or otherwise endorsed by any third party.
About The Author