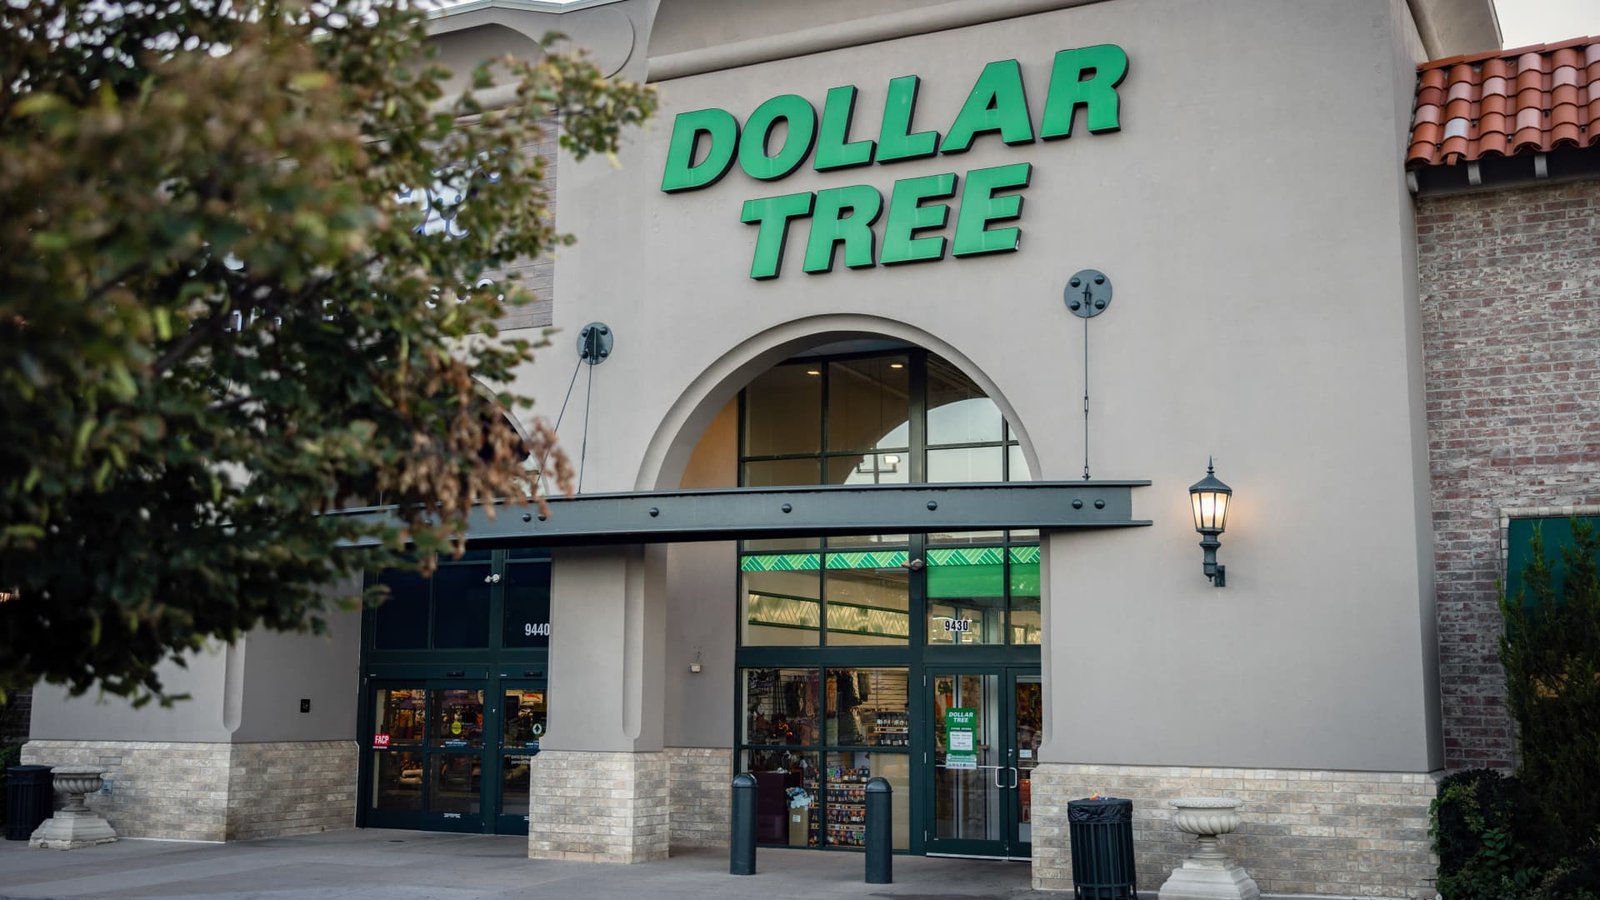
Dollar Tree is likely to get a boost to its business amid an uncertain macroeconomic backdrop, driving its shares higher, according to Loop Capital. The investment bank upgraded the discount retailer to buy from hold, raising its 12-month price target to $140 from $130, implying roughly 23% upside from Wednesday’s close. “We believe the current U.S. macroeconomic backdrop is highly favorable for Dollar Tree as the holiday selling season approaches, and think the ongoing multi-price initiative is a sustainable comparable store net sales growth driver,” analyst Anthony Chukumba wrote Thursday in a note to clients. “[O]ur current bullish fundamental outlook and stepped-up stockholder returns warrant a higher valuation.” Shares of Dollar Tree are down more than 13% in the past month, hurt by rising gasoline prices and fading consumer purchasing power. DLTR 1M mountain Dollar Tree is down more than 13% in the past month The recent decline in consumer confidence should prove “highly favorable” to the dollar store’s efforts to attract more customers and boost sales, according to Loop Capital. In addition, Dollar Tree finally put the disastrous $9 billion purchase of Family Dollar in 2015 behind it in 2025 when it sold the division for $1 billion, freeing up capital to invest in new initiatives, the analyst said. “Having finally put the Family Dollar acquisition firmly in the rear-view mirror, Dollar Tree has ramped up EPS accretive share repurchases,” Chukumba wrote. Loop Capital’s recommendation goes against consensus on the Street, where 15 of 29 analysts rate Dollar Tree a hold and 10 are at buy or strong buy, LSEG data shows.