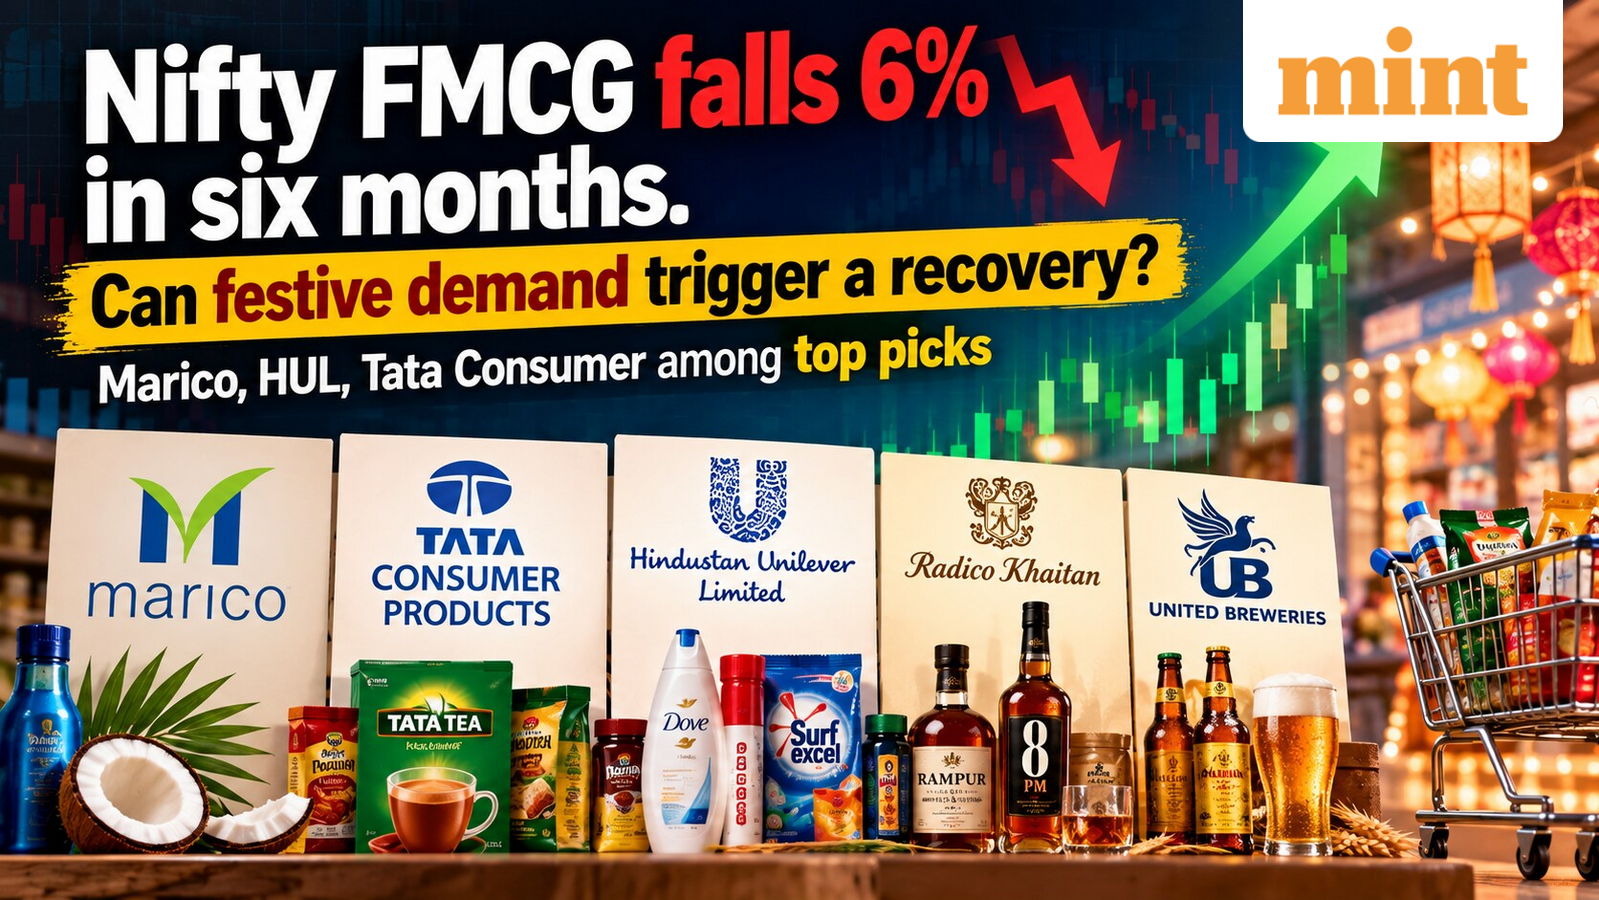
The Nifty FMCG index has declined 6% over the past six months, covering the first half of FY27, underperforming the Nifty 50, which fell over 1% during the same period. The sector has faced pressure from weak price momentum, rising input costs and concerns over margins, even as underlying demand and volume growth have started to improve.
With the festive season approaching, analysts expect consumer demand to pick up, but believe the recovery may not be uniform across the sector. Softening raw material prices, improving volumes, and a favourable festive demand environment could support select stocks, while companies facing higher input costs or elevated taxation may continue to see margin pressure.
Brokerages and technical analysts are therefore advocating a stock-specific approach, with Marico, Tata Consumer, HUL, Radico Khaitan and United Breweries among the names highlighted by analysts and Nuvama Institutional Equities.
Festive season could support FMCG demand
Sunny Agrawal, Deputy Vice President – Fundamental Research at SBI Securities, said the upcoming festive season should provide a supportive demand environment for FMCG companies, as consumer spending typically gains traction during this period.
However, he expects the benefit to vary across companies depending on their earnings outlook and raw material exposure.
Marico could be one of the key beneficiaries, with the recent softening in copra prices likely to support its margins and earnings in Q2FY27 and the second half of FY27, Agrawal said.
He also remains constructive on Nestlé, Tata Consumer and Pidilite, despite elevated crude oil prices, and expects these companies to perform relatively better within the sector.
On the other hand, companies that benefited from low-cost inventory in Q1FY27 could face higher input costs in the September quarter. Agrawal expects Bajaj Consumer to see some moderation in Q2 due to rising input costs.
For ITC, he expects a sequential improvement in earnings, although year-on-year performance could remain under pressure because the steep increase in taxation has only been partly offset by price hikes. Further price increases are expected in the second half of FY27, but a complete recovery in margins could take time.
“Overall, we believe a selective, stock-specific approach would be the right way to play the FMCG sector during the festive season,” Agrawal said.
Nuvama sees double-digit sales growth in Q2FY27
Nuvama Institutional Equities expects double-digit sales growth for most staples and paint companies in Q2FY27, supported by a healthy mix of pricing and volume growth and a favourable base.
According to Nuvama, several staples companies could also benefit from a soft base, as consumers and channel partners had deferred purchases in the final week of September last year amid the GST transition.
The brokerage noted that pricing has largely normalised to pre-GST levels across staples. FMCG companies have taken around 5% price hikes, broadly reversing the impact of GST cuts, while Asian Paints has implemented double-digit price increases and Pidilite has taken cumulative hikes of around 11%.
Nuvama expects the festive demand pattern to be different this year because Diwali falls later, around 10 November. As a result, demand for paints, snacks, sweets and gifting products could shift from Q2 into Q3.
For paints, the brokerage expects demand to improve in Q3, with the end of the monsoon before Diwali likely to provide better drying conditions. This could, however, result in some marginal demand softness in Q2.
Marico stands out as raw material costs ease
Nuvama expects Marico to benefit from the softening in copra prices and has included the stock among its top buys for the quarter.
The brokerage’s top BUY picks for Q2FY27 are Marico, Radico Khaitan, United Breweries, Tata Consumer and HUL.
Nuvama also expects Marico, Nestlé, Bajaj Consumer, United Breweries and Varun Beverages to deliver relatively strong September-quarter results.
However, the brokerage cautioned that the benefit of low-cost inventory seen in Q1FY27 has largely run its course. Consequently, most FMCG companies could face gross-margin pressure in Q2 as input costs rise.
Marico could be an exception because of lower copra prices, while Britannia may face pressure from higher sugar, palm oil and milk costs. Pidilite’s EBITDA margin is estimated at around 22%.
ITC faces a different earnings trajectory
ITC’s cigarette business remains a key area of focus. Nuvama expects cigarette volumes to decline around 8% year-on-year, while cigarette net revenue and EBIT could fall approximately 23% and 27%, respectively, in Q2FY27.
The brokerage expects some improvement compared with Q1, as ITC has already taken price hikes across a large part of its portfolio, with further increases expected in the second half.
However, the steep increase in taxation continues to weigh on the business, meaning a complete margin recovery could take time.
Technical charts remain under pressure
From a technical perspective, the FMCG index continues to show weakness.
Sudeep Shah, Vice President – Technical and Derivatives Research at SBI Securities, said the index faced strong resistance around its 20-day EMA before reversing sharply lower. It has now slipped below its earlier swing lows of 44,825 and 45,334.
The index is trading nearly 2.5% below its 20-day EMA and around 10% below its 200-day EMA, indicating a weak underlying trend, according to Shah.
The RSI has fallen below 40 on both the daily and weekly timeframes, while a rising ADX on the weekly chart points to strengthening downside momentum.
Shah identified 45,550–45,600 as the immediate resistance zone and said the bearish bias is likely to persist as long as the index remains below this level.
Analysts see selective opportunities despite weak charts
Rajesh Bhosale, Technical Analyst at My Advisor Alpha, said the FMCG sector is currently in an uncomfortable phase, with the Nifty FMCG index down around 2% in H1FY27 and nearly 23% below its 52-week high.
He noted that most of the decline has occurred in recent months, with the index’s April rally subsequently being erased by a sharp fall in the September quarter.
However, Bhosale pointed to an improvement in the underlying business environment, with sector revenue growth accelerating to around 15% year-on-year in Q1FY27 from 11% in Q4FY26, alongside signs of volume recovery.
Rather than taking exposure across the entire sector, Bhosale favours a selective approach. He highlighted VBL, Radico Khaitan, ITC and HUL as stocks placed near long-term support zones and showing relative strength against the index.
He noted that Radico Khaitan, for instance, gained around 11% during the quarter while the FMCG index declined around 11%.
Can festive demand trigger a sector recovery?
The outlook for FMCG stocks, therefore, remains mixed. Improving volumes and festive demand could provide a catalyst for the sector, but higher input costs could limit margin expansion for several companies.
Nuvama expects its coverage universe, excluding ITC, to deliver 15% revenue growth, 11% EBITDA growth and 9% volume growth in Q2FY27, compared with 15%, 20% and 10%, respectively, in Q1FY27.
At the same time, the brokerage flagged monsoon deficiency as a risk for second-half demand.
With the technical picture still weak but earnings and volumes showing signs of improvement, analysts broadly point to a selective rather than sector-wide approach as investors assess whether the festive season can translate into a sustained recovery in FMCG stocks.
Disclaimer: This story is for educational purposes only. The views and recommendations above are those of individual analysts or broking companies, not Mint. We advise investors to check with certified experts before making any investment decisions.
About The Author