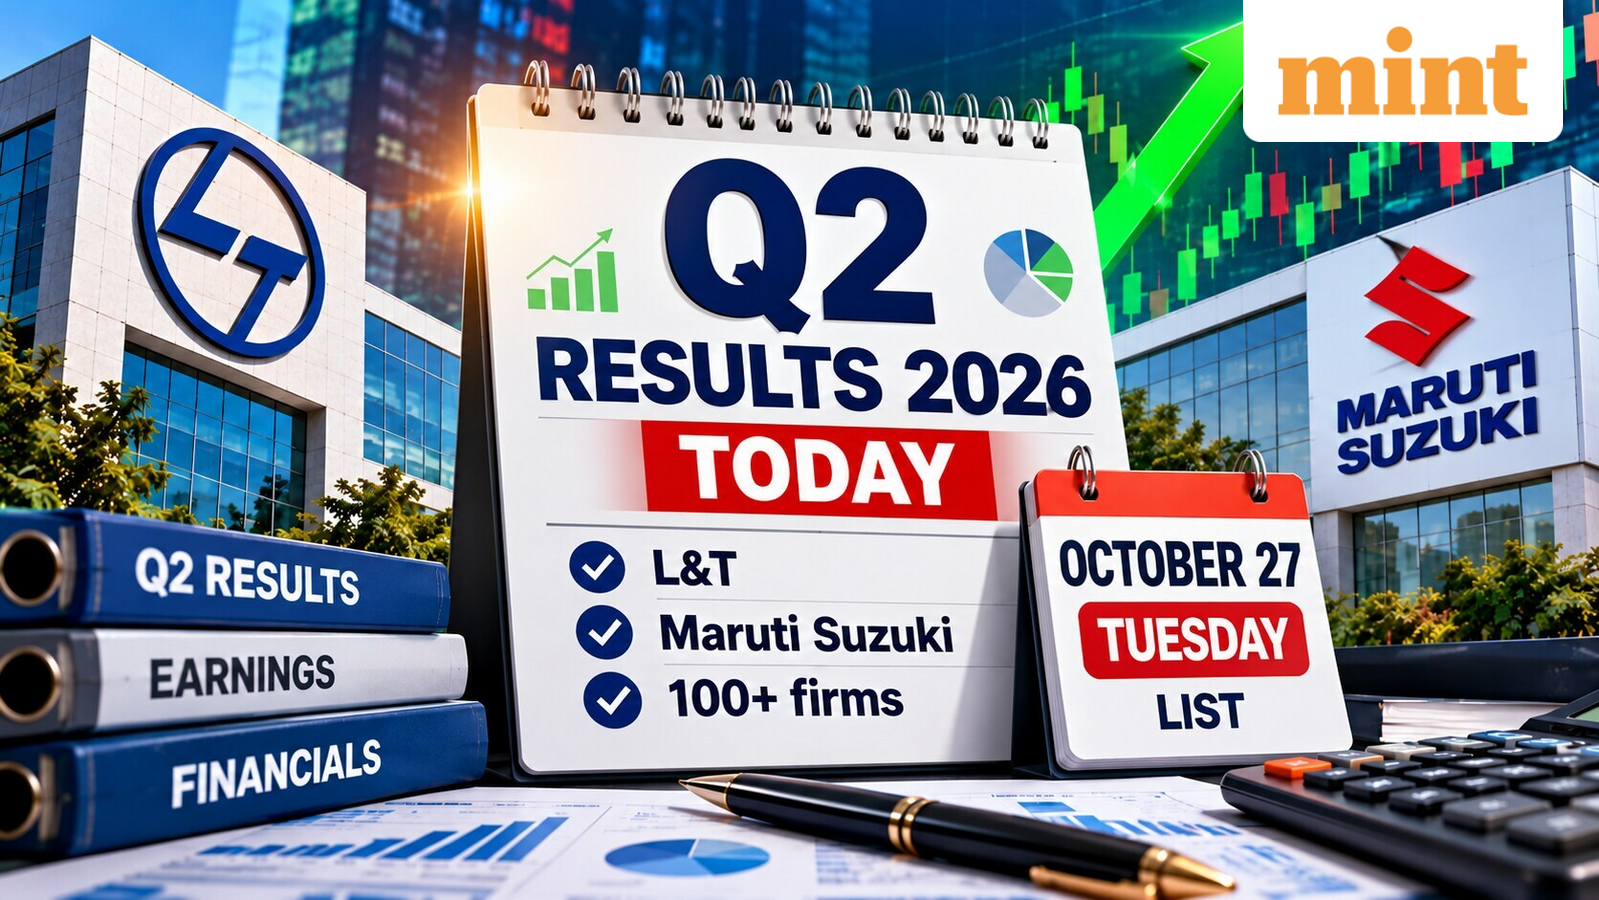
Q2 results 2026 today, schedule: The Q2 earnings season for the financial year 2026-27 (Q2 FY27) will continue on Tuesday, October 27, with over 100 companies scheduled to release their financial results for the July-September quarter.
Key companies announcing their quarterly earnings today include Larsen & Toubro (L&T), Maruti Suzuki, Bajaj Auto, Tata Steel, Cipla, Tata Capital, Indus Towers, Mazagon Dock Shipbuilders.
Investors will closely monitor these results for updates on revenue growth, net profit and operating margins. Management commentary will also be in focus for clues about business performance, future outlook and growth prospects.
Brokerage firm Kotak Institutional Equities expects the core EPC business to report 8% year-on-year growth, factoring in disruptions to overseas execution due to the Middle East war and a limited recovery in domestic water projects. Most execution sites in the Middle East are progressing well so far, supported by existing inventory levels. The brokerage expects order inflows to reach around ₹1.3 trillion, equivalent to 1.3 times the order inflows announced so far and 2.5 times core revenues. It has assumed no profit contribution from Nabha Power following its recent divestment.
The brokerage expects EBITDA margin in the core engineering and construction (E&C) business to decline to 7% from 7.3% a year ago, owing to slower execution, modest inflation in raw material prices and temporarily higher logistics costs, which could reverse in subsequent quarters. However, savings in interest costs following the Nabha Power divestment are expected to support profit after tax (PAT) growth from the current quarter.
Maruti Suzuki Q2 results 2026 preview
Axis Direct Maruti Suzuki expects total revenue to increase by around 29.8% year-on-year, supported by a 26.5% rise in volumes and a 3% improvement in average selling prices (ASPs) over the past year. Growth is likely to be aided by a favourable product mix, with utility vehicles (UVs) accounting for 34% of the mix in Q2FY27, up from 28% in Q2FY26. A stronger export mix and contributions from new product launches are also expected to support revenue growth.
It further projects EBITDA margins to expand by around 37 basis points year-on-year but contract by 195 basis points sequentially. Elevated raw material costs and supply chain disruptions are likely to weigh on margins, partly offset by higher sales of new models and increased export volumes.
Bajaj Auto Q2 results 2026 preview
The brokerage firm expects Bajaj Auto’s total revenue to grow around 26% year-on-year and 9% quarter-on-quarter, supported by a 20% YoY and 8% QoQ increase in overall volumes. Rupee depreciation is likely to support exports, while a favourable product mix and price hikes are expected to drive improvement in average selling prices (ASPs).
EBITDA margins are projected to remain largely flat year-on-year but decline by 40 basis points sequentially. Higher raw material and commodity costs, particularly aluminium and other metals, are expected to weigh on margins, partly offset by stronger export volumes.
Disclaimer: We advise investors to check with certified experts before making any investment decisions.
About The Author