GE Vernova shares slip despite a beat-and-raise. What the sellers are getting wrong
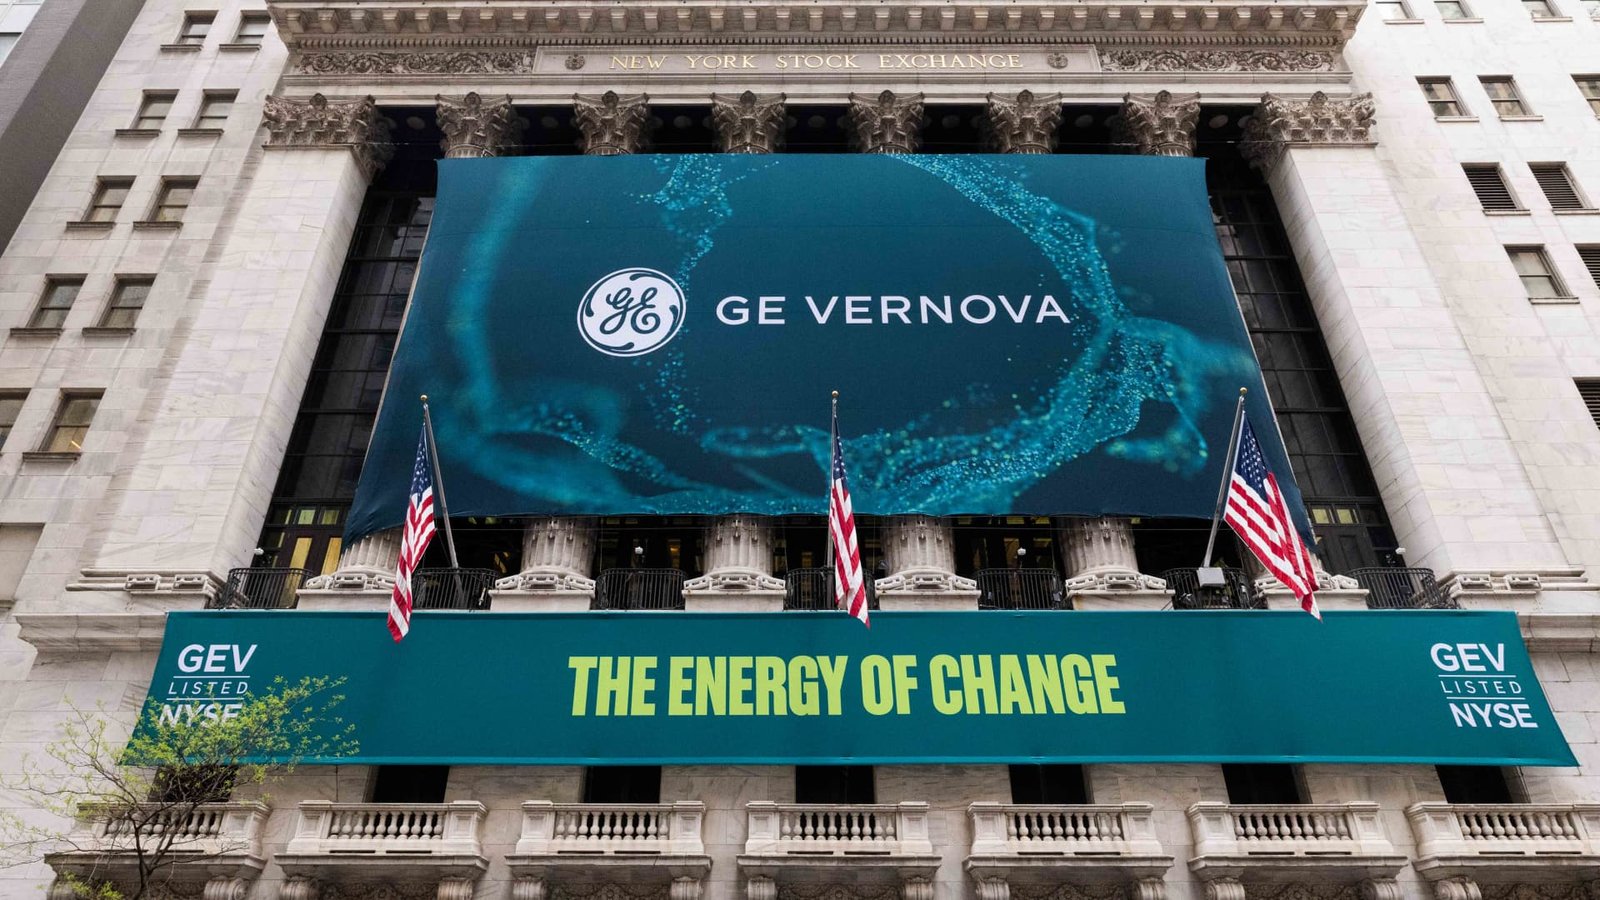
GE Vernova shares fell Wednesday despite the gas turbine maker delivering a beat-and-raise quarter and announcing a smart acquisition to fortify its future into the end of the decade.The sellers may be taking issue with the order-growth trajectory for next year, but that looks short-sighted when taking a holistic view of the company’s business. Revenue in the third quarter ended Sept. 30 increased about 27% year over year to $12.64 billion, topping expectations of $11.99 billion, according to LSEG. Earnings per share (EPS) increased 193% to $4.81, exceeding the LSEG consensus estimate of $3.94 apiece. GEV YTD mountain GE Vernova’s year-to-date stock performance. Bottom Line Last earnings go-round in July , GE Vernova missed the mark on profits per share and the stock tumbled 8.7%. However, we argued investors should look past the bottom-line miss and focus instead on the strong order growth, arguing it was the true indicator of demand. Admittedly, GE Vernova hasn’t been a great performer since then, struggling to gain its footing along with many other stocks levered to the buildout of artificial intelligence infrastructure. We’ve added to our position twice (in August and last week), believing the price action wasn’t reflecting the strength of the company’s underlying business. We think that’s what is happening again Wednesday, because the third-quarter results point to no letup in demand. The company delivered a very strong quarter characterized by better-than-expected order growth, leading to significant sequential backlog expansion, and strong cash flow performance. Oh yeah, GEV also outpaced expectations on top-line revenue, organic sales growth, earnings, and a measure of operating profitability known as EBITDA (earnings before interest, taxes, depreciation, and amortization). With one quarter left to go in 2026, management also increased its full-year outlook for sales, EBITDA and free cash flow. We’re also big fans of the deal to buy Trench Group, a privately held maker of electric-grid equipment. So, why are shares down? That’s an obvious question to ask, especially because the stock was initially higher in premarket trading Wednesday morning. But then the conference call got underway, and the sellers took control. We think there are two comments to highlight that could be driving the weakness. Keep in mind that GEV investors want to see continued strong pricing for gas turbines, in the face of the supply-demand imbalance, because that helps drive margin expansion and profit growth. And they also want to see continued order and backlog growth as a signal that this boom isn’t peaking. The first earnings call comment was about pricing within the all-important Gas Power segment. During the prepared remarks session, CEO Scott Strazik said the company expects gas equipment orders in the fourth quarter to have a price-per-kilowatt below third-quarter levels “due to fewer aeroderivatives and relatively more 50 Hertz units.” That outlook is based on the expected conversion of slot-reservation agreements (SRAs) into firm orders. The second is Gas Power growth next year. Asked about 2027, Strazik said, “As we look into 2027, although it’s hard to call the quarters, per se, at this point, we certainly continue to see real growth in our gigawatts on contract throughout 2027, but that maybe the quarterly profiles in 2027 are more likely to feel like 3Q and 4Q than they may have felt in 1Q and 2Q, but with an ability for us to materially continue to grow both our backlog and our gigawatts on contractthroughout next year.” So, while GE Vernova executives still see growth ahead, some investors appear to be taking issue with the cadence of that growth. For context, in the first quarter of 2026, the company signed 21 gigawatts of new gas equipment contracts, encompassing both firm orders and slot reservation agreements. That figure was 20 GW in the second quarter and 11 GW in the third quarter. And the company guided to 13 GW in the ongoing fourth quarter. In other words, this could be a situation of a good 2027, but not good enough. We think that viewpoint is too critical and certainly not enough to justify Wednesday’s pullback considering the stock came into the release down 13% since the Oct. 6 close and down another 9% since its July 22 earnings sell-off. (In afternoon trading, shares have moved nicely off their lows of the morning.) Therefore, we believe this a buying opportunity for those willing to ride out the negative sentiment currently weighing on anything and everything tied to the data center. That complex has been hurt in recent months by higher interest rates, AI funding concerns and political pushback. During the quarter, GEV’s Gas Power backlog grew from 116 to 122 GW, and the team now expects to exit the year with a 130 GW backlog. Back in April, the expectation was to end the year at least 110 GW; the target was then increased to 125 GW in July, underscoring how demand has strengthened throughout the year. In dollar terms, the team booked $29.3 billion in orders, a 96% year-over-year increase (up $20.4 billion sequentially). This resulted in a book-to-bill ratio of more than 2 and a backlog exiting the quarter of roughly $197 billion. A ratio greater than 1 means that the company took orders faster than it could deliver on them, translating to backlog growth that helps increase visibility into future revenue. Lastly, the board of directors also doubled GEV’s buyback authorization to $20 billion. As for the prior $10 billion, Strazik said, “After investing$1.6 billion of the buyback in3Q and over$1.3 billion in October,we have largely completed our $10 billion authorization with excellent returns, having acquired 15.6 million shares at an average price of approximately$635.” That’s more than $200 below where the stock is trading Wednesday and more than $500 below its all-time closing high in June. We reiterate our buy-equivalent 1 rating. However, we are trimming our price target to $1,200 (from $1,300) in an acknowledgement that the negative sentiment is compressing valuation multiples across AI buildout names. Trench acquisition GE Vernova said its $9 billion acquisition of privately held Trench Group should close in late 2027. The deal, which will be funded by an even share of cash and debt, is expected to be immediately accretive and lead to about $50 to $100 million in annualized cost efficiency savings by 2030, in addition to the cross-selling revenue opportunities it will provide GEV. The move underscores the increasing importance of GE Vernova’s Electrification segment, which we highlighted back in July. While its gas turbines may be the big revenue driver — and play a critical role in generating power — the company’s grid equipment is how that generated power gets transported to where it is consumed. Key products include switchgear, transformers, power capacitors and even grid software . Trench, in particular, will strengthen GE Vernova’s core offerings in high- and medium-voltage markets. One of Trench’s most important products is bushings, a type of insulator that are a key component in Vernova’s power transformers. Wednesday’s announcement comes eight months after GE Vernova enhanced the Electrification segment by acquiring the remaining stake in transformer manufacturer Prolec for $5 billion. Although data centers are a big part of the demand story for Electrification, there’s a broader need to modernize the grid with higher-voltage equipment to reduce energy loss and handle load growth from electric vehicles, heat pumps and manufacturing. On Wednesday’s earnings call, Strazik said that earlier last year, he felt there were two key electrification assets missing from GEV’s portfolio. The first was Prolec, which the team said Wednesday is performing ahead of expectations as they successfully deliver on both cost and revenue synergies; owning the rest of Prolec helps the company better compete in the North American market. The second was Trench, which brings differentiated technology, a strong management team, and, as an existing GEV supplier, adds vertical integration. The team expects the Prolec integration to be substantially complete by the time Trench closes, which should help reduce any concerns about execution risk of two acquisitions within a short period of time. GEV expects its existing total addressable market (TAM) in electrification to reach about $300 billion by 2030. Importantly, the high-voltage equipment market that Trench plays into makes up about $130 billion of that overall number (40%). Owning Trench will help GEV capture more of that market. In 2026, GEV expects to sell about $300 million in bushings, instrument transformers and coils. Trench is expected to sell about $1.4 billion across those three product lines, with management expecting that to grow to about $2 billion in 2028. Trench currently has a roughly $2.6 billion backlog, with about $2.4 billion in additional framework agreements. Management also expects Trench’s adjusted EBITDA margin to expand from about 33% in 2026 to about 36% by 2028, with free cash flow about doubling in that time to roughly $400 million. Quarterly commentary Power Organic orders increased 178% year over year Organic revenue growth led by gas power equipment 830 basis points of organic EBITDA margin expansion year over year 3 GW of orders and 8 GW of SRAs signed in the quarter Shipped 5 GW of equipment and converted 13 GW from SRAs to orders Backlog now consists of 64 GW of orders and 58 GW of SRAs Electrification Organic orders decreased 9% year over year Organic revenue growth driven by grid systems integration and power transmission. 470 basis points of organic EBITDA margin expansion year over year Book-to-bill of 1.4 times Wind Organic orders increased 16% year over year. Organic revenue growth driven by onshore wind services and offshore wind equipment. 420 basis points of organic EBITDA margin expansion year over year. Guidance Here’s GE Vernova’s revised guidance for 2026: Revenue in the range of $46.5 to $47.5 billion (up from $45.5 to $46.5 billion), and ahead of the $46.3 billion estimate, according to LSEG. Adjusted EBITDA margin in the range of 13.5% to 14.5% for the year (up from 12% to 14%). The revised midpoint is above the FactSet consensus of 13.7%. Free cash flow between $16 and $17 billion (up from $11.5 billion to $12.5 billion), well ahead of estimates for $12.4 billion, according to FactSet. Driving the upward revenue revision, management now expects: Power to deliver 19% to 21% organic revenue growth (up from 18% to 20% previously), with EBITDA margins between 19% to 21% (up from 17% to 19%). Electrification sales are reaffirmed in the range of $14.5 billion to $15 billion. However, this now includes a $3.1 billion contribution from Prolec (up from an expected $3 billion before). While the EBITDA margin target remained at 18% to 20%, the company expects it to skew toward the higher end of that range. Wind organic revenue declining in the mid-single digits (versus a low-double digit decline previously forecast). (Jim Cramer’s Charitable Trust is long GEV. See here for a full list of the stocks.) As a subscriber to the CNBC Investing Club with Jim Cramer, you will receive a trade alert before Jim makes a trade. Jim waits 45 minutes after sending a trade alert before buying or selling a stock in his charitable trust’s portfolio. If Jim has talked about a stock on CNBC TV, he waits 72 hours after issuing the trade alert before executing the trade. THE ABOVE INVESTING CLUB INFORMATION IS SUBJECT TO OUR TERMS AND CONDITIONS AND PRIVACY POLICY , TOGETHER WITH OUR DISCLAIMER . NO FIDUCIARY OBLIGATION OR DUTY EXISTS, OR IS CREATED, BY VIRTUE OF YOUR RECEIPT OF ANY INFORMATION PROVIDED IN CONNECTION WITH THE INVESTING CLUB. NO SPECIFIC OUTCOME OR PROFIT IS GUARANTEED.