Despite mortgage rates over 7.0%, fallcould be a great time to get a deal on a home if you know how to negotiate.
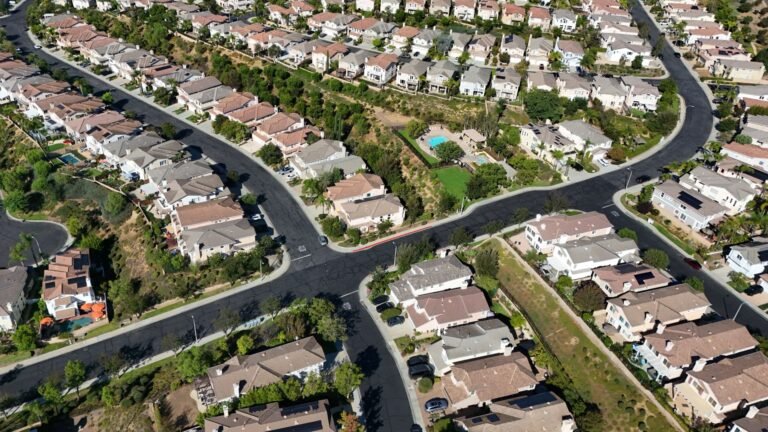
High rates push some buyers out of the market and, as demand slows, the number of listings usually growsand prices soften, giving house hunters more power. As a result, sellers may be more willing to cut prices or cover closing costs to ink a deal.
For the week ending Oct. 17, inventory grew 7.7% and the median listing price fell 2.1% compared to last year, according to Realtor.com. What’s more, 22% of sellers with active listings dropped their asking price, the highest level in Redfin’s records.
“Buyers who are able to be in the market despite difficult financing conditions may be able to secure a home at a price that is lower than asking,” Realtor.com senior economist Jake Krimmel told CNBC Select in September 2026.
Here are four tips forgetting the best deal possible — plus, lenders that offer some of these options.
Talk to us
Are you living paycheck to paycheck, or do you have a financial success you’re comfortable sharing with a reporter? Please fill out this quick form.
Look at homes that have been on the market for a while
Sellers with listings on the market for over 30 days may be more likely to cuttheir price.
If you’re looking to submit an offer under asking or negotiate a price cut, ask your realtor aboutproperties that have been on the market for a month or two.
You can also view days on market data on sites like Realtor.com, Redfin and Zillow.
See if the seller will cover closing costs
If you really love a house but the seller won’t budge on price, see if they’ll offer other incentives to sweeten the deal.
One major expense that sellers can help with is closing costs — or the bill due when you sign your papers on closing day, including underwriting, appraisal and title-search fees.Closing costs typically range from 2% to 6% of the mortgage amount.
Certain loan programs are specifically designed to help sellers do this. Through Truist‘s Community Homeownership Incentive Program (CHIP), sellers can contribute up to 6% of closing costs in certain geographic areas.
Truist Mortgage
-
Annual Percentage Rate (APR)
Apply online for personalized rates; fixed-rate and adjustable-rate mortgages are available.
-
Types of loans
Conventional loans, FHA loans, VA loans, USDA loans, Jumbo loans, investment loans, low-down-payment mortgages, home equity lines of credit
-
Terms
15- to 30-year fixed-term conventional loans, 5/1, 7/1 or 10/1 adjustable rate loans
-
Credit needed
-
Minimum down payment
0% for VA and USDA, 3.5% for FHA, 3% for conventional, 10% for jumbo
Investigate seller rate buydowns
You can also ask a seller to temporarily buy down your rate. There are three common types of temporary rate buydown programs:
- 1-0 buydown: Interest rate effectively drops by 1% in the first year and then reverts to the original rate in the second year.
- 2-1 buydown: Interest rate effectively drops 2% in the first year, 1% in the second and returns to its original in the third.
- 3-2-1 buydown: Interest rate effectively drops by 3% the first year, 2% the second year, 1% the third year and back to the original rate in the fourth year.
To be sure, there are downsides. Unlike a home price drop or a closing cost contribution, which is a permanent discount, your rate will jump up when the temporary buydown period ends. Be certain you can make the monthly payment before choosing that structure.
If you’re interested in these programs, certain lenders offer seller-specific rate buydowns.
Rocket Mortgage, for example, offers a 3-2-1 buydown that can be funded by the seller. Rocket is also known for its quality customer service and easy-to-use website.
Rocket Mortgage
-
Annual Percentage Rate (APR)
Apply online for personalized rates; fixed-rate and adjustable-rate mortgages are available.
-
Types of loans
Conventional loans, FHA loans, VA loans, Jumbo loans, low-down-payment mortgages
-
Terms
10-, 15- and 30-year fixed-term conventional loans, 30-year VA and FHA loans, custom mortgages with fixed-rate terms from 8 to 29 years.
-
Credit needed
620 for conventional loans
-
Minimum down payment
0% for VA, 1% for RocketONE+, 3% for conventional, 3.5% for FHA, 10% to 15% for jumbo
Chase Bank also offers a seller-funded buydown for one to three years. If you’re looking for an in-person experience, Chase has over 5,000 retail locations nationwide.
Chase Bank Mortgage
-
Annual Percentage Rate (APR)
Apply online for personalized rates; fixed-rate and adjustable-rate mortgages included
-
Types of loans
Conventional loans, FHA loans, VA loans, DreaMaker℠ loans and Jumbo loans
-
Terms
-
Credit needed
-
Minimum down payment
3% if moving forward with a DreaMaker℠ loan
-
Offers first-time homebuyer assistance?
Be flexible on the closing date
The seller may be more apt to provide these incentives if you make the process easier for them.
For example, because of their own home-buying timeline, a seller may needto close very quickly or may need more time than usual. Let them know, during the negotiation, that if they provide incentives, you could give them that flexibility.
You may also want to offer a rent-back agreement — when the buyer allows the seller to stay in the home for a fee over a period of time after closing.
Subscribe to the CNBC Select Newsletter!
The CNBC Select Recommends newsletter delivers practical money tips each week along with expert-picked financial product recommendations. Sign uphere.
Why trust CNBC Select?
At CNBC Select, our mission is to deliver high-quality service journalism and comprehensive consumer advice to our readers, enabling them to make informed financial decisions. Every mortgage review is based on rigorous reporting by our team of expert writers and editors with extensive knowledge of financial products. While CNBC Select earns a commission from affiliate partners on many offers and links, we create all our content without input from our commercial team or any outside third parties and we pride ourselves on our journalistic standards and ethics.
Catch up on CNBC Select’s in-depth coverage ofcredit cards,bankingandmoney and follow us onTikTok,Facebook,InstagramandXto stay up to date.
Editorial Note: Opinions, analyses, reviews or recommendations expressed in this article are those of the Select editorial staff’s alone, and have not been reviewed, approved or otherwise endorsed by any third party.
About The Author