We're raising our price target on Cardinal Health after another stellar quarter of profits
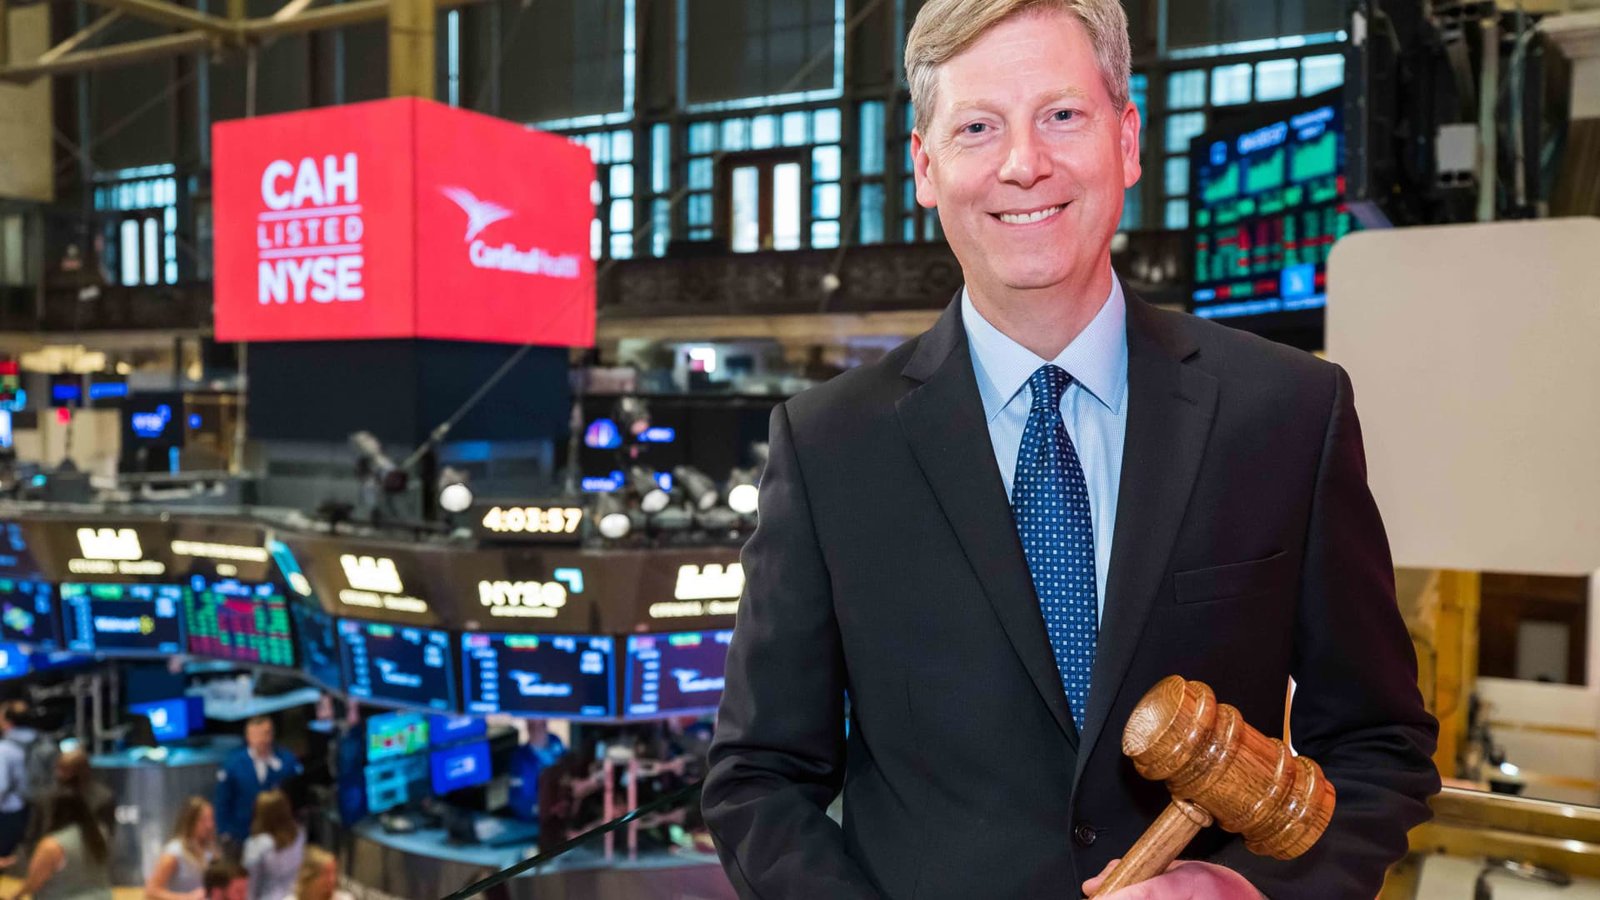
Cardinal Health on Thursday reported a beat-and-raise quarter to kick off its new fiscal year, further solidifying the healthcare distributor as an underappreciated yet attractive defensive stock to own. Revenue in Cardinal’s fiscal 2027 first quarter totaled $67.51 billion, up 4% year over year, and ahead of the $66.6 billion consensus, according to LSEG. Adjusted earnings per share (EPS) rose 28% on an annual basis to $3.26, well ahead of the $2.94 consensus, LSEG data showed. CAH YTD mountain Cardinal Health’s year-to-date stock performance. Shares of Cardinal Health were up more than 3% on Thursday, off their highs of the session but still one of the few bright spots amid the market’s steep sell-off. We booked big profits in Cardinal and Eli Lilly . We have loved these stocks all year as a way to diversify beyond the AI trade. We remain long-term believers, but the trims were out of discipline. Bottom line Cardinal Health turned in a cleaner quarter than last time around in August. The highlight was its largest operating segment — Pharmaceutical and Specialty Solutions — getting back to exceeding both sales and profit expectations in the quarter, paired with an improved outlook for the rest of the year. Better yet, just one quarter into its fiscal 2027, Cardinal raised its full-year adjusted EPS guidance, an encouraging sign of confidence in the overall business outlook. Investors covet Cardinal for its track record of consistent earnings growth, and that doesn’t appear to be changing anytime soon. Expectations were elevated into the print, thanks to Cardinal shares closing Wednesday at a record high and its two main rivals, Cencora and McKesson , reporting better-than-expected results within the past 24 hours. And yet, Cardinal cleared the lofty bar and shares are surging higher. Some of Thursday’s gains may be due to the fact that Cardinal is not a tech stock, as money again flows out of AI trade winners and investors look to buy companies that don’t rely on the data center boom to beat expectations. That doesn’t detract from the quality of Cardinal’s results, especially within its bread-and-butter Pharmaceutical and Specialty Solutions segment. It does, however, make us want to opportunistically trim into this strength. Accordingly, we peeled off 50 shares earlier Thursday. On the earnings call, CEO Jason Hollar said the Pharma business benefited from strong unit demand for both generic medications and specialty therapeutics (treatments for cancer, as well as urological, kidney and autoimmune diseases). Hollar said the specialty business, a key long-term growth driver for the industry, grew at a high-teens clip in the quarter. “Importantly, that strength was coming from some key priority areas, particularly urology and oncology,” he said. The Pharma unit also includes Cardinal’s managed services organizations (MSOs), the industry term for owning the business side of medical practices. Cardinal has made a few acquisitions in recent years to build up its MSO presence, and it’s one of the more exciting long-term growth opportunities. Management talked positively about their integration progress in the September quarter and later indicated they see the opportunity for additional M & A in this space, without committing to anything concrete. Still, it was encouraging to hear that Cardinal sees the ability to get bigger in MSOs. One blemish on the first-quarter results: Cardinal’s fastest-growing, highest-margin Other segment missed on both revenue and operating profit. Though the smallest of the three by revenue, the Other segment is home to the strategically important businesses of nuclear pharmacies, direct-to-patient delivery, and its OptiFreight third-party logistics business for hospitals, labs, and other healthcare facilities. Our thesis in the stock is predicated, in part, on Cardinal Health having transformed into more than just a sleepy, low-margin distributor of pharmaceuticals and medical supplies to hospitals and retail pharmacies. Along with the MSOs, the Other segment businesses are critical to that transformation as they benefit from long-term trends such as an aging population, shifts to home-based care, and more complex treatments like radiopharmaceuticals hitting the market. Cardinal’s third segment — Global Medical Products and Distribution — wasn’t anything to write home about. Though operating profit of $33 million was above expectations, it represented a 28% decline from the year-ago quarter. This business, which covers the manufacture and distribution of medical, surgical and lab products (rather than drugs), had faced pressure from tariffs and now is being squeezed by elevated petroleum costs. The upshot is that Cardinal has been working on improving the segment’s performance, and management indicated that progress is occurring. Bigger picture, we were pleased that Cardinal said within the past 12 months, the company has renewed contracts representing nearly two-thirds of its enterprise revenue. That includes the renewal with CVS Health announced on Oct. 1 , which proved to be a clearing event of sorts for the stock because the company also reaffirmed its guidance alongside the announcement. Hollar said the agreement with CVS underscores the valuable service that Cardinal provides the pharmacy chain, which “will continue beyond the spin-off in 2028.” On Wednesday, CVS announced plans to split into two separate public companies — pharmacy in one and its Aetna insurance business and pharmacy benefit manager in the other. Cardinal also repurchased $500 million worth of stock in the quarter — half of the $1 billion in buybacks the company had previously signaled for fiscal 2027. CFO Aaron Alt said Cardinal has the flexibility to consider where to deploy its cash flow during the rest of the year, “whether that is incremental M & A … or further return of capital to shareholders.” We’re reiterating our hold-equivalent 2 rating, but raising our price target to $300 a share from $265. Guidance Cardinal Health revised its full-year outlook on a couple of key metrics: Adjusted EPS in the range of $12.80 to $13.00, an increase from its prior guide of $12.40 to $12.60. The new midpoint of $12.90 is above the $12.57 estimate on FactSet and implies 18% year-over-year growth when excluding tariff refund benefits in fiscal 2026 earnings. Pharmaceutical and Specialty Solutions segment profit growth between 10% to 12%, up from 8% to 11% previously. That’s above the implied consensus of 9.6% growth. Other segment revenue growth in the range of 12% to 14%, an increase from previous expectations of 11% to 13% growth. The midpoint of 13% is a beat versus the consensus of 12.2% growth. Other segment profit growth between 17% and 20%, versus 15% to 18% growth previously. The midpoint of 18.5% exceeds expectations of 16.9% growth. There was no change to Cardinal’s expectations for the Global Medical Products and Distribution segment. The company continued to guide for revenue growth of 3% at the midpoint and segment profit between $200 million and $220 million. The company also continues to expect adjusted free cash flow between $3.5 billion and $4 billion. (Jim Cramer’s Charitable Trust is long CAH. See here for a full list of the stocks.) As a subscriber to the CNBC Investing Club with Jim Cramer, you will receive a trade alert before Jim makes a trade. Jim waits 45 minutes after sending a trade alert before buying or selling a stock in his charitable trust’s portfolio. If Jim has talked about a stock on CNBC TV, he waits 72 hours after issuing the trade alert before executing the trade. THE ABOVE INVESTING CLUB INFORMATION IS SUBJECT TO OUR TERMS AND CONDITIONS AND PRIVACY POLICY , TOGETHER WITH OUR DISCLAIMER . NO FIDUCIARY OBLIGATION OR DUTY EXISTS, OR IS CREATED, BY VIRTUE OF YOUR RECEIPT OF ANY INFORMATION PROVIDED IN CONNECTION WITH THE INVESTING CLUB. NO SPECIFIC OUTCOME OR PROFIT IS GUARANTEED.