Terms apply to American Express benefits and offers. Visit americanexpress.com to learn more.
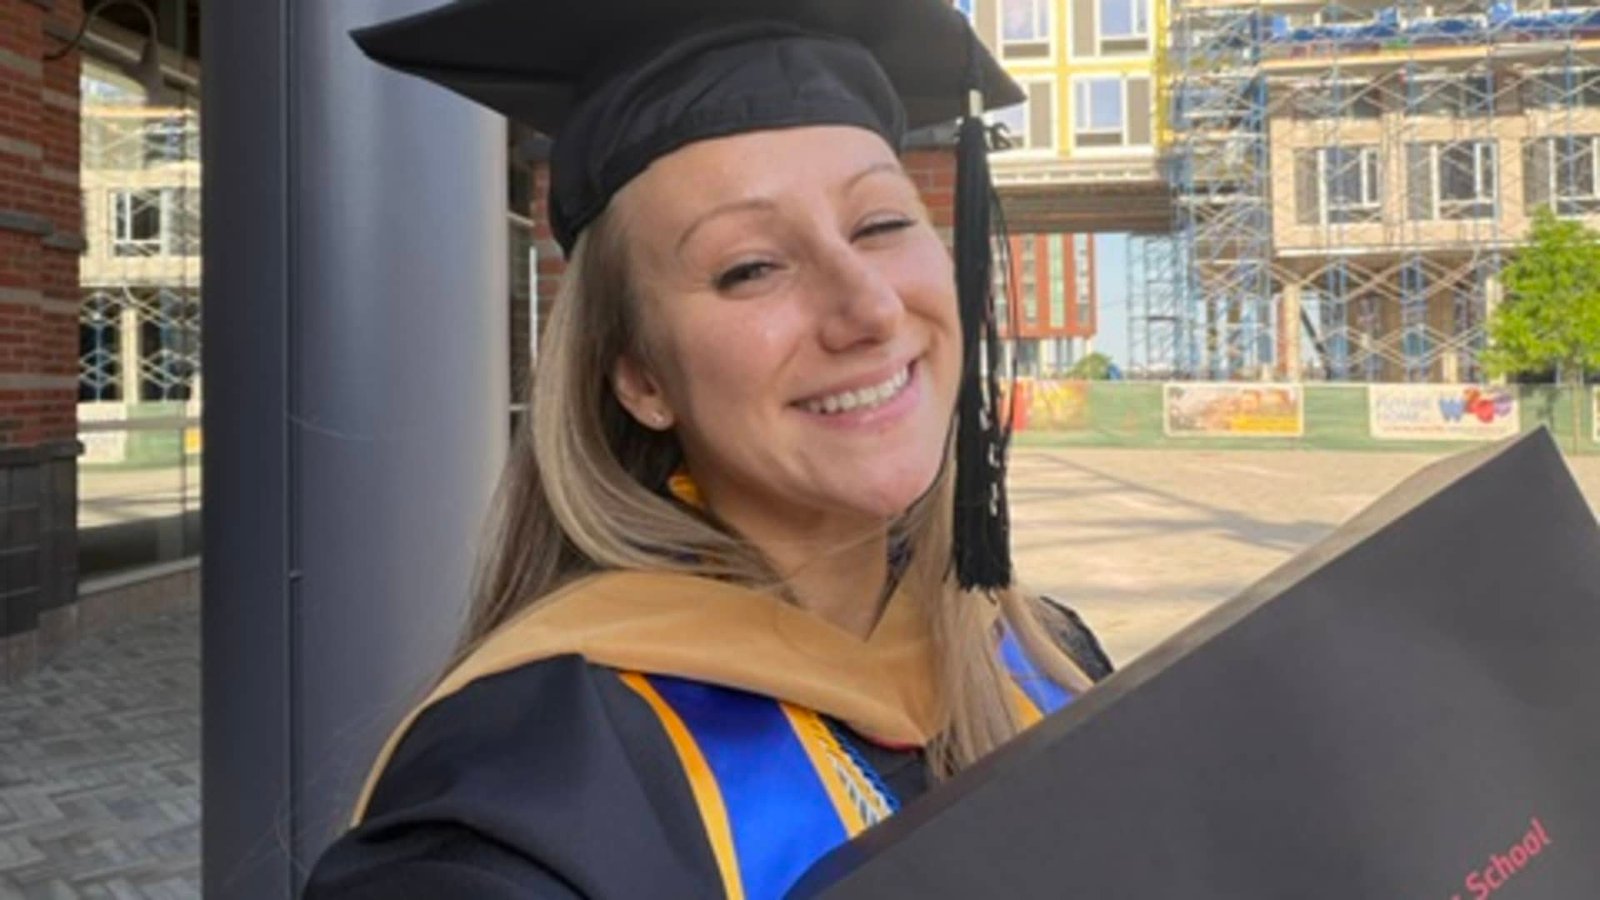
Ashley Thompson would love to splurge on fun purchases, but despite her and her partner making over six figures between them, they still can’t find room in their budget.
“We bring our coffee to work in the morning,” Thompson told CNBC Select. “I don’t get my nails done. I don’t get my hair done… I don’t know how people do it and go on vacations.”
Together, 37-year-old Thompson and her partner of nine years make between $150,000 and $300,000 together. In addition to mortgage payments starting on Oct. 1, Thompson is actively paying down over $32,000 in student loan debt and covering a $340 monthly car payment on her 2025 Volkswagen Tiguan.
Ashley Thompson
Courtesy of Ashley Thompson
When the pair first began looking for a house together, they quickly realized the often-referenced 20% down payment guideline wasn’t realistic for them. Even with the lower initial payment they ended up with, her partner was concerned about whether they could make it work.
“He was genuinely like, ‘Are we gonna be able to afford this?’ And I’m like, I think so,” she said.
To try and stretch their funds, Thompson assessed their budget to see what could be removed or improved. Instead of doing a weekly shopping trip to their local grocery store, Thompson signed up for a Costco membership, which lets them save by buying food in bulk. And when they make purchases, she and her partner consider whether they have a credit card that’ll earn rewards back on that spending. Thompson also looked at their recurring subscriptions, which are a common contributor to lifestyle creep.
“We definitely canceled Apple and Hulu as far as subscriptions,” she said. “I canceled my gym membership. I had a fitness app that I had to cancel… I just don’t use it enough to get the value out of it.”
Arguably, the most important opportunity cost for Thompson is losing the ability to save for the future, at least right now.
“I have not contributed [to my retirement] at all this year,” she said.
Thompson isn’t the only one feeling financially pinched. A July CNBC and SurveyMonkey Quarterly Money Survey found 41% of Americans making between $100,000 and $249,999 are living paycheck to paycheck. And of those people living paycheck to paycheck, 90% have less than $500 left over each month.
While earning six figures can be the start of a strong financial base, it’s not quite the brag it used to be. Comparing 2006 and 2026 consumer price index (CPI) data, overall consumer prices are 64% higher than they were 20 years ago. Another way to look at it: $100,000 today has the same buying power as roughly $60,900 in 2006.
If you’re in a similar boat — living paycheck to paycheck (or close to it) with a six-figure salary — consider one of these methods to help build a buffer.
3 tools to consider if your six-figure income feels tight
Western Alliance Bank High-Yield Savings Account
Western Alliance Bank is a Member FDIC.
-
Annual Percentage Yield (APY)
3.80% APY
-
Minimum balance
$1 minimum deposit
-
Monthly fee
None
-
Maximum transactions
Up to 6 transactions each month
-
Excessive transactions fee
The bank may charge fees for non-sufficient funds
-
Overdraft fee
No overdraft fee
-
Offer checking account?
No
-
Offer ATM card?
No
Terms apply.
Pros
- Earns a strong APY with no caps, so every dollar in your account is earning the full rate regardless of your balance.
- Minimum opening deposit of just $1.
- No monthly fees and no overdraft fees, so nothing is cutting into your earnings.
Cons
- No checking account or ATM access, so this works best as a dedicated savings account paired with another bank.
- Non-sufficient funds fees may apply, so it’s worth keeping an eye on your balance before making transfers.
Rewarding credit cards
For Ashley, making sure she was earning rewards on purchases was key. There are a variety of rewards credit cards that earn flat-rate or bonus category rewards on everyday spending, from groceries to gas to dining out.
If you’re newer to rewards credit cards or want a simple way to earn, the Citi Double Cash® Card earns a flat 2% cash back on all purchases. You’ll earn 1% when you buy, and the other 1% when you pay, meaning you’ll earn cash back on every purchase without having to track rewards categories.
If, like Ashley, you’re reconsidering how you shop for groceries, how you pay could be just as important for helping you save.
According to 2021 and 2026 CPI data, the price of groceries (food at home) has increased by 23.7% between these years; $100 worth of groceries in 2021 would now cost you $123.70. While it may seem simple, paying with the right credit card can help you manage some of these rising prices.
The Blue Cash Everyday® Card from American Express earns some of the strongest grocery rewards: 6% cash back on up to $6,000 per year at U.S. supermarkets (then 1%), or up to $360 back each year. The cash back you earn can be redeemed as a statement credit or for Amazon purchases.
Unforeseen emergencies like a car breaking down or medical bills can be devastating for someone living paycheck to paycheck. In a situation like that, a 0% APR card could be the right fit, allowing you to delay any interest payments and pay off your purchase over time.
The Wells Fargo Reflect Card offers a 0% intro APR for 21 months from account opening on both purchases and qualifying balance transfers. After the introductory rate ends, a 17.49%, 23.99% or 28.24% variable APR applies.
Home equity line of credit
Homeowners who have been paying their mortgage for a while now could have a substantial bit of equity built up, which can be tapped into responsibly.
A home equity line of credit, or HELOC, lets you borrow against the equity you’ve built in your home as a revolving line of credit. HELOC rates are typically much lower than those of credit cards because you’re using your home as collateral, so repayments are critical.
A HELOC through Figure is unique as you can complete your entire HELOC process from the comfort of your own home. You can borrow up to $750,000 and access the funds in as few as five days.
Figure
-
Loan types
HELOC, DSCR, cash-out refinance, crypto-backed loan, small business loans
-
Minimum credit score
600
-
Maximum loan-to-value
85%
-
HELOC draw amount
$15,000 to $750,000
-
HELOC draw period
2 years or 5 years
-
Repayment period
10 years, 15 years, 20 years, 30 years
-
Availability
Figure HELOCs are available in all states but Hawaii.
Pros
- Funding as soon as 5 days, much shorter than most fund timelines so you’ll get your money as soon as possible.
- E-closing available, which means you can tap your home equity from your couch.
- No opening fees, prepayment fees or maintenance fees, saving you on closing costs and ongoing costs over the life of the financing
- High LTV maximum, meaning that you’ll be able to maximize the amount you take out.
Cons
- Not available in all states
- Maximum draw period is five years
Available APRs range from 6.75% to 14.35%, which includes the payment of a higher origination fee in exchange for a reduced interest rate, which is not available to all applicants or in all states. The lowest APRs are only available to the most qualified applicants, depending on credit profile and the state where the property is located, and those who also select ten year loan terms; APRs will be higher for other applicants and those who select longer loan terms. Your actual rate will depend on many factors such as your credit, combined loan-to-value ratio, loan term, occupancy status, and whether you are eligible for and choose to pay a higher origination fee in exchange for a lower rate. Rates change frequently so your exact APR will depend on the date you apply. APRs for home equity lines of credit do not include costs other than interest. You will be responsible for an origination fee of up to 4.99% of your initial draw, depending on the state in which your property is located and your credit profile. You may also be responsible for paying the costs of valuation if an AVM is not available for your property ($180), or an appraisal if your loan amount exceeds $400,000 ($500-$2,000, depending on property type, property value, and state), manual notarization if your county doesn’t permit eNotary ($350), and recording fees ($0 – $315) and recording taxes, which vary by state and county ($0- $1,400 per one hundred thousand dollars borrowed). Property insurance is required as a condition of the loan and flood insurance may be required if your property is located in a flood zone.
Subscribe to the CNBC Select Newsletter!
The CNBC Select Recommends newsletter delivers practical money tips each week along with expert-picked financial product recommendations. Sign up here.
Why trust CNBC Select?
At CNBC Select, our mission is to provide our readers with high-quality service journalism and comprehensive consumer advice so they can make informed decisions with their money. Every financial article is based on rigorous reporting by our team of expert writers and editors with extensive knowledge of financial products. While CNBC Select earns a commission from affiliate partners on many offers and links, we create all our content without input from our commercial team or any outside third parties, and we pride ourselves on our journalistic standards and ethics.
Catch up on CNBC Select’s in-depth coverage ofcredit cards,bankingandmoney, and follow us onTikTok,Facebook,InstagramandXto stay up to date.
For rates and fees of the Blue Cash Everyday® Card from American Express, click here.
Editorial Note: Opinions, analyses, reviews or recommendations expressed in this article are those of the Select editorial staff’s alone, and have not been reviewed, approved or otherwise endorsed by any third party.
About The Author