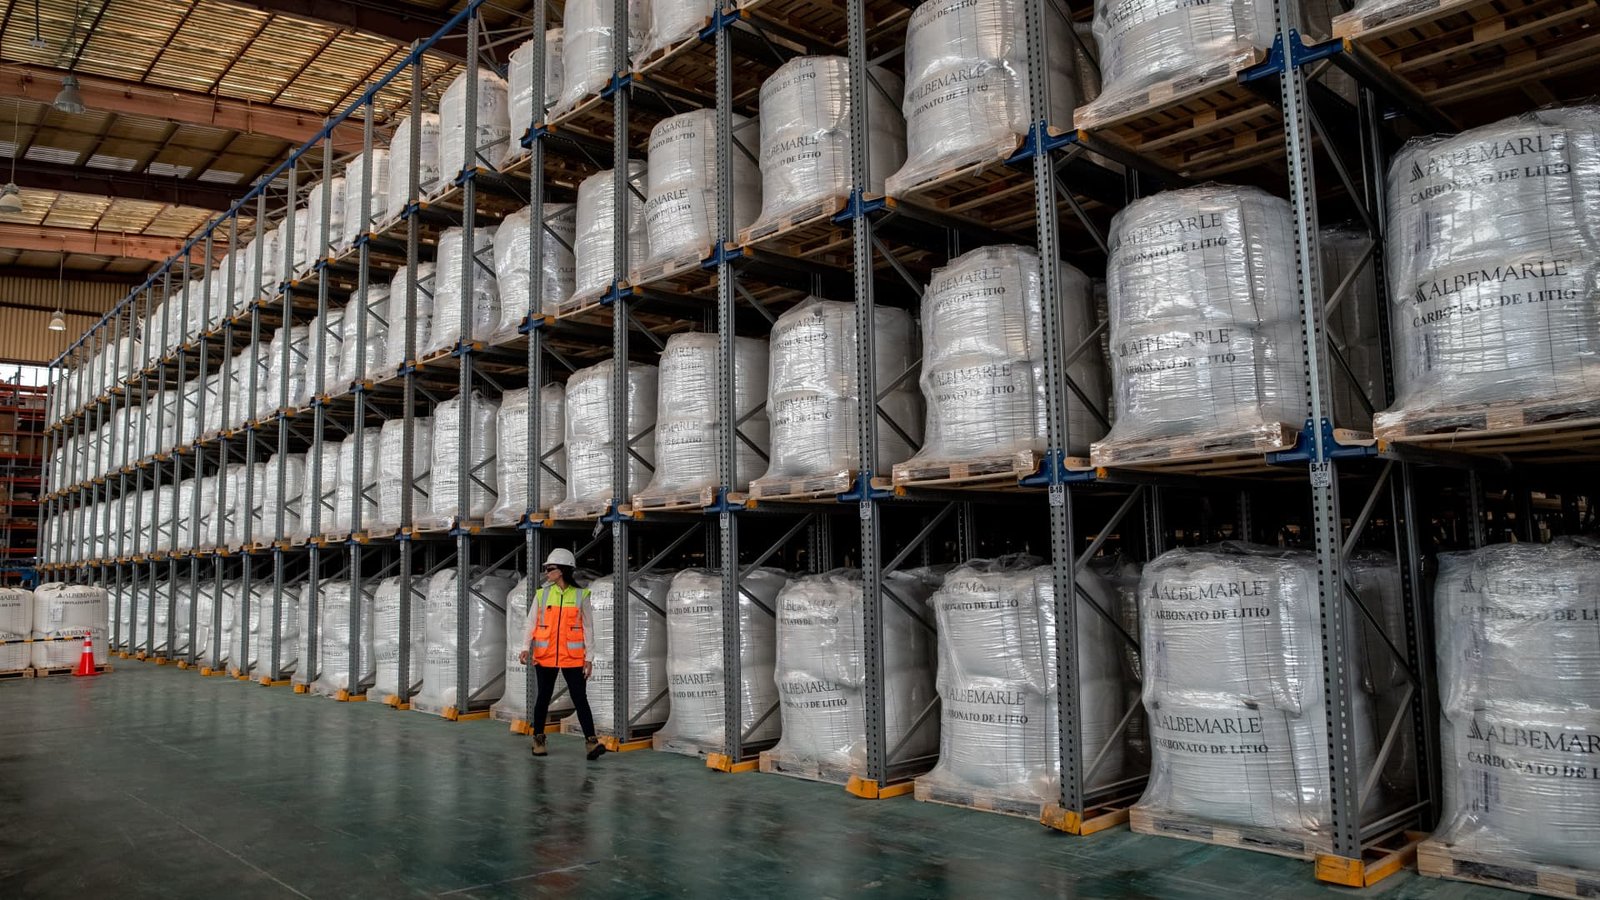
Albemarle is likely to bounce back as lithium demand grows, according to Mizuho. The investment bank upgraded the lithium miner to outperform from neutral. It has a $130 price target on shares, suggesting 33% upside from Tuesday’s close. “We are raising ALB rating to Outperform as strong Battery Energy Stationary Storage (BESS) demand has tipped market balance into favorable territory,” analyst John Roberts said Tuesday in a note to clients. “ALB is the lowest-cost lithium producer and its improved balance sheet provides downside resilience while providing flexibility to invest as project returns improve.” Shares have fallen 31% year to date, partially due to weakness in lithium prices. Lithium is a raw material used to manufacture batteries. ALB YTD mountain Shares are down 31% in 2026. Lithium carbonate’s price is expected to rise to $22,500 from $18,375 per metric ton by the end of 2027, according to Mizuho. Lithium demand could become even more intense if regulatory roadblocks delay the resumption of Contemporary Amperex Technology’s upstream production, per Roberts. “Lithium remains a volatile, capital-intensive commodity, but the near-term supply/demand outlook has tightened as … demand continues to exceed expectations while new supply is constrained by long project lead times and reduced industry capital spending,” the analyst wrote. Mizuho’s call falls in line with consensus on the Street. Of the 23 analysts covering Albemarle, 15 have a buy or strong buy on the stock, while eight have a hold rating on it, LSEG data shows.