India’s drone industry is moving beyond being a niche defence technology into a strategically important part of the country’s military procurement architecture, and analysts expect this shift to create a multi-year opportunity for domestic drone manufacturers.
Ashika Institutional Research said drones had reached an inflection point following Operation Sindoor, the Russia-Ukraine war and conflicts in West Asia.
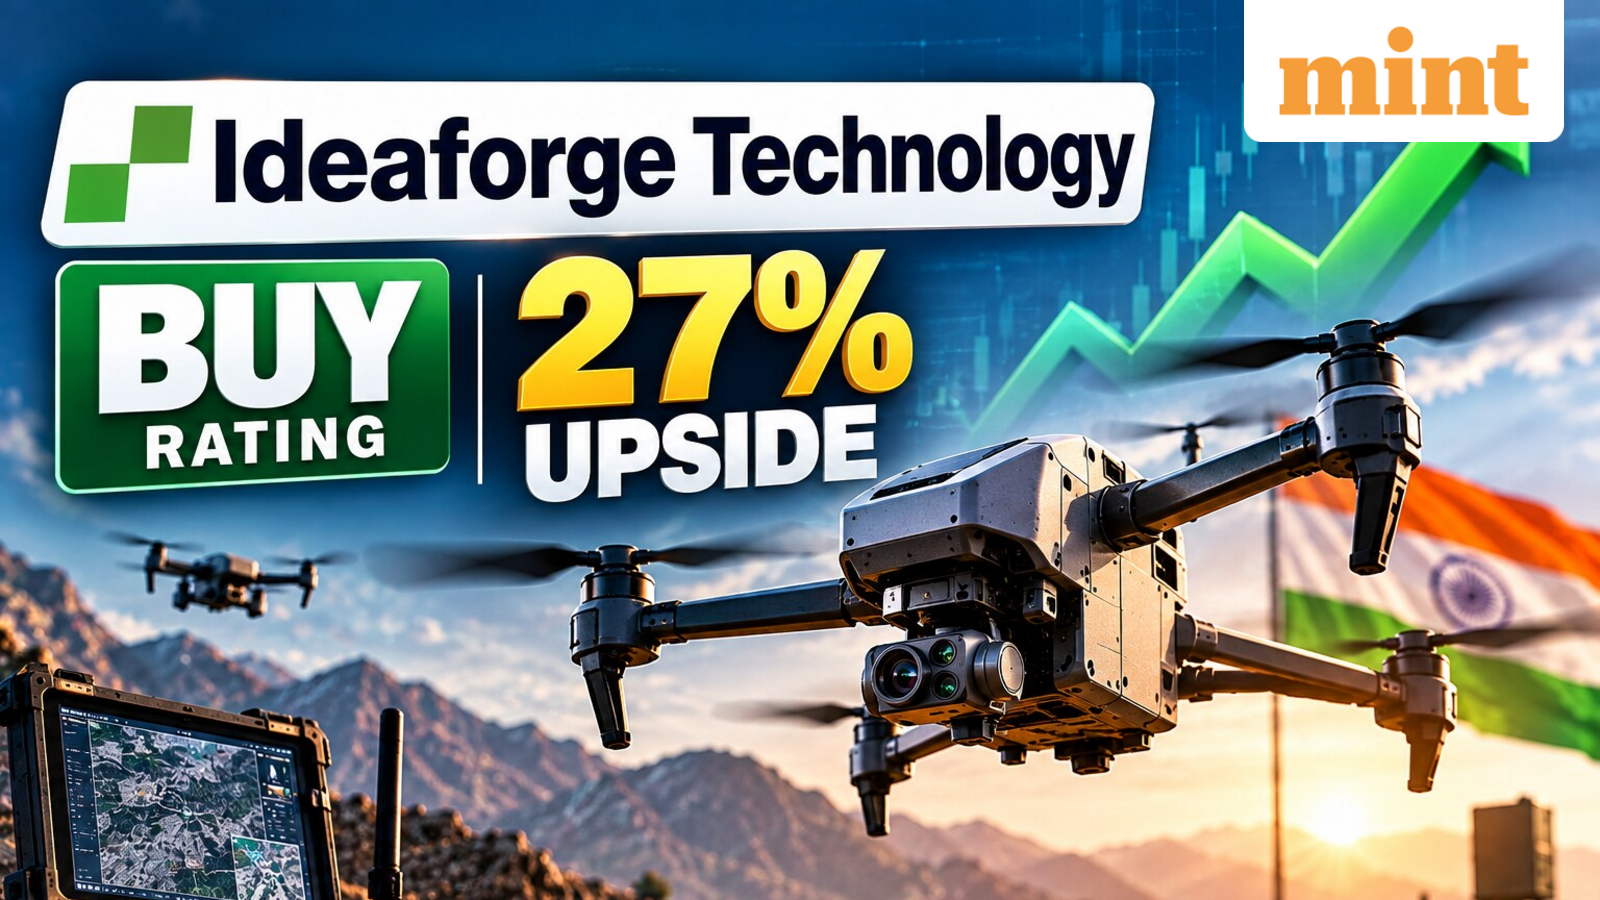
The brokerage initiated coverage on ideaForge Technology with a BUY rating and a target price of ₹942, compared with its then current market price of ₹741, implying 27% upside.
The brokerage’s thesis was built around rising defence procurement, a protected domestic market, Ideaforge’s technology capabilities and a sharp improvement in profitability as revenue scales.
“The investment case is fundamentally an operating leverage story – fixed employee costs and other expenses not growing as much as revenue nearly doubling each year will drive EBITDA margin from 2% to 29% over two years,” it said.
Ashika valued the company at 32x FY28E P/E, based on estimated FY28 earnings per share of ₹29.4, to arrive at its ₹942 target price. The brokerage said the valuation was supported by a sub-1.0 PEG, its position within the 30–65x peer P/E range and a scarcity premium for India’s sole listed pure-play drone manufacturer.
The drone stock has lost 7.5% in 1 month and 11.5% in 3 months. Meanwhile, in 6 months, it advanced over 80% while added 38.5% in the last 1 year. LTP at Trading at ₹730.90, the stock is currently 27% away from its 52-week high of ₹997, hit in June 2026. Meanwhile, it touched its 52-week low of ₹367.95 in March 2026.
Reasons for bullishness
Ashika highlighted the ₹200 billion Fast Track Procurement (FTP) pipeline as a major near-term catalyst for the sector. The pipeline covers armed unmanned aerial vehicles (UAVs), loitering munitions, intelligence, surveillance and reconnaissance (ISR) platforms, counter-drone systems and Medium Altitude Long Endurance (MALE) systems. Under Defence Procurement Manual 2025, the FTP pipeline is structurally accessible to domestic manufacturers.
“Operation Sindoor (May 2025) transformed Indian Defence Drone procurement from budgetary to existential priority. The Indian Army’s largest-ever drone order (>Rs200bn) represents a multi-year revenue visibility at current scale. EW resilience is now a baseline procurement criterion,” said Ashika Institutional Equities Research
The report said Ideaforge was positioned to benefit from this shift because defence accounted for 69% of its FY26 revenue and the company supplied UAVs to the Indian Army, paramilitary and police forces.
Ashika also pointed to Ideaforge’s electronic warfare resilience stack, including Controlled Reception Pattern Antenna (CRPA) anti-jamming, Visual Positioning System (VPS) and secure communications. The brokerage said the company had invested in the technology three to four years before it became a procurement requirement. According to the report, management had indicated that positive signals from the field could accelerate order activity from Q3FY27.
“India’s Fast Track Procurement pipeline of Rs200bn ($2.4bn) is the largest single drone sector procurement catalyst in the country’s history, and it is legally accessible only to domestic manufacturers under DPM 2025,” informed the brokerage.
Estimates and target price
Ashika expected Ideaforge’s revenue to rise from ₹2,261 million in FY26 to ₹4,252 million in FY27 and ₹8,084 million in FY28, translating into year-on-year growth of 40.3%, 88% and 90%, respectively.
The sharper improvement was expected at the operating-profit level. EBITDA was estimated to increase from ₹48 million in FY26 to ₹685 million in FY27 and ₹2,349 million in FY28. This would take the EBITDA margin from 2.1% in FY26 to 16.1% in FY27 and 29.1% in FY28.
Ashika estimated adjusted profit after tax (APAT) at a loss of ₹170 million in FY26, followed by ₹206 million in FY27 and ₹1,459 million in FY28. EPS was projected at a loss of ₹3.9 in FY26, ₹4.2 in FY27 and ₹29.4 in FY28.
Technical View
Sachin Gupta, VP – Technical Research at Choice Equity Broking noted that IDEAFORGE has taken support from the previous support zone formed on 4th May on the daily chart and witnessed a bounce from its long-term 200 EMA, currently placed at ₹692.77.
“The price action near this key moving average indicates buying interest at lower levels and provides an important base for the ongoing recovery. However, the Daily RSI at 41.53 remains below the neutral 50 mark, indicating that momentum is yet to turn decisively positive and remains relatively weak.
On the upside, ₹782.88 is the key resistance level, coinciding with the 50 EMA and likely to act as an important hurdle for the stock. A sustained move above this level would improve the short-term technical structure and could support further recovery,” he added.
On the downside, the 200 EMA around ₹692.77 remains the crucial support level to watch. Overall, the setup shows a recovery from long-term support, but stronger momentum would require a decisive breakout above the resistance zone, stated the expert.
Disclaimer: The views and recommendations made above are those of individual analysts or broking companies, and not of Mint. We advise investors to check with certified experts before making any investment decisions.
About The Author