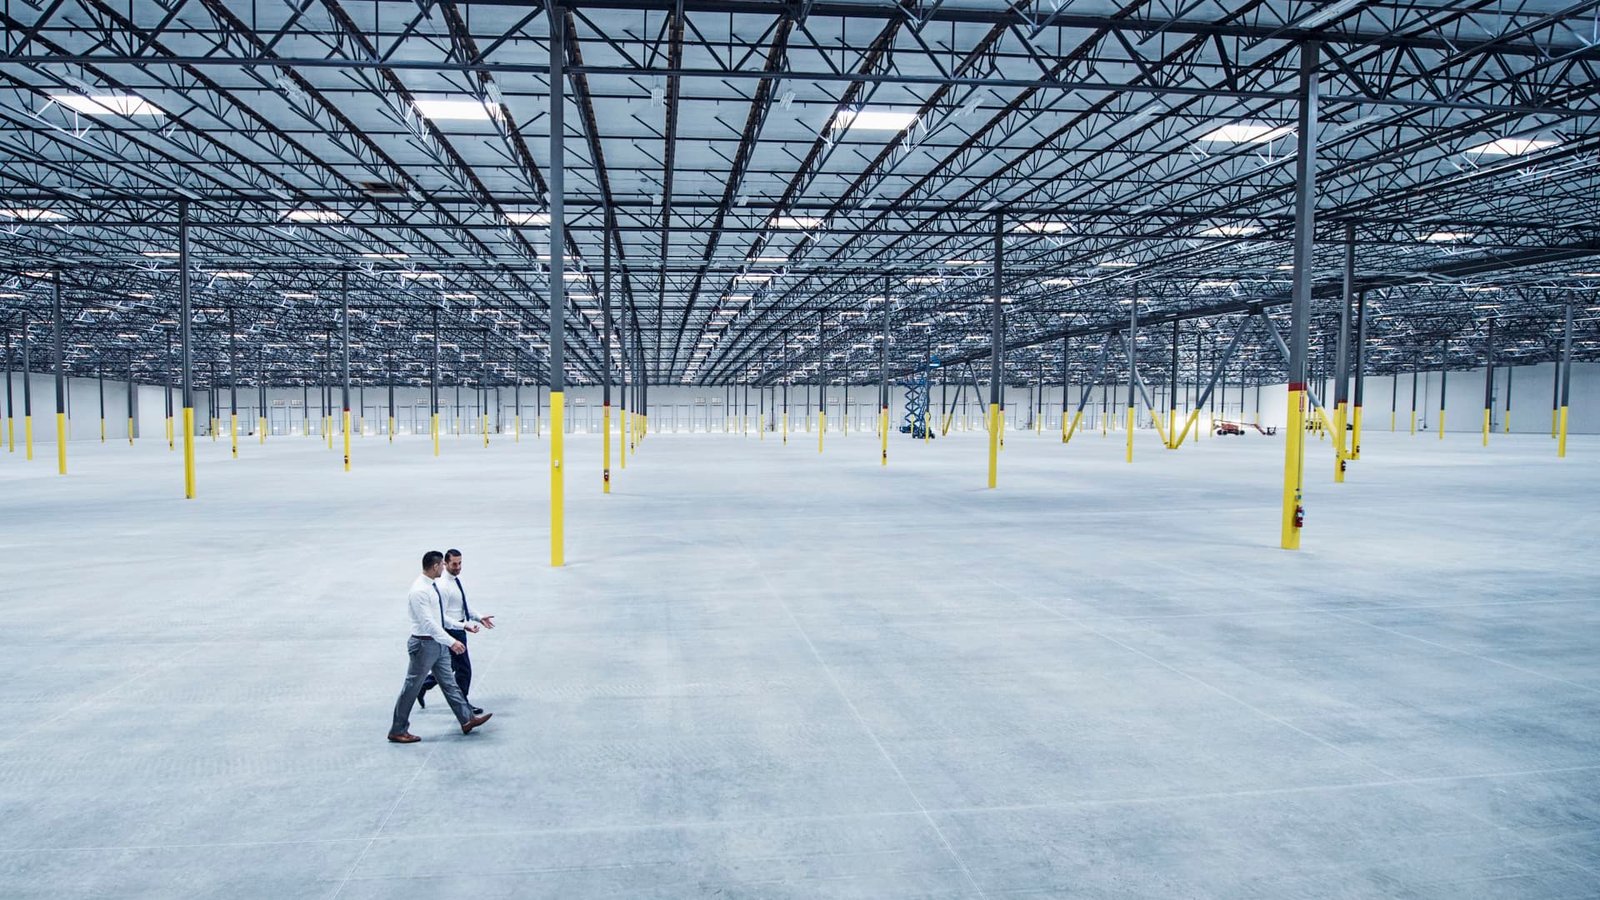
Erik Isakson | Tetra Images | Getty Images
A version of this article appeared in CNBC’s Inside Wealth newsletter, a weekly guide to the high-net-worth investor and consumer.Sign upto receive future editions, straight to your inbox.
Higher interest rates have made family offices more selective about investing in real estate, with many focusing on highly discounted properties and assets with strong pricing power, chief investment officers told CNBC.
Rob Haugen of Michels Family Office said uncertainty over where interest rates are headed has made the firm pickier about investing in the asset class. Haugen oversees private capital investments, mergers and acquisitions at the family office and is also the chief investment officer of its spinout firm River1 Asset Management.
“Honestly, until we have really strong conviction that rates are headed back down, it’s difficult for us to want to do anything except the really special project,” he said.
Haugen said he typically targets opportunities with potential yields on cost in the high single-digit or double-digits. This is possible with buying an office building at a heavy discount with a known tenant that will occupy a lot of the real estate, he said. Another opportunistic avenue is big-box retail spaces, he said. About a year and a half ago, the family office bought a Kohl’s near Milwaukee with an investor consortium, according to Haugen.
Joel Houck, chief investment officer of HB Wealth, said that he has seen an uptick in interest from large family offices in real estate and real assets more broadly, such as industrial warehouses, farmland and timberland. Certain types of real estate and real assets offer protection against inflation, he said, which is a top concern for many family offices.
Investors can also get more bang for their buck as these assets are tax-efficient, according to Houck. For instance, it is possible to use a depreciation shield to defer paying taxes on distributions until the asset is actually sold, he said.
However, real estate’s potential to hedge inflation depends on its pricing power and structure.
“With real estate, your inflation protection comes from the ability of the underlying property manager to reset rental rates,” Houck said. “With different asset subclasses like multifamily, industrial, retail, not all rents are reset at the same rate.”
Industrial real estate and housing both offer the ability to raise rents on a regular basis, he said. Both asset classes can benefit from supply constraints, Houck added.
Higher rates can create opportunities to buy assets at a discount, but investors also need to watch how much debt a fund uses, he noted. HB Wealth generally steers clients away from funds with leverage above 65%, whether at the operating property or fund level.
And while family investors are curious about investing in the real estate and real assets around data centers, many are wary of the commitment it requires. Haugen is wary of entering a 10- to 15-year lock up at high interest rates.
Mike Silverman, chief investment officer at Cresset, said that clients ask about data centers frequently, but the wealth advisory firm hasn’t pursued those opportunities due to the risk.
“I would tend to think of data centers as being a more of a technology investment than a real estate investment,” he said. “You’re investing in a 15-year lease with a major company. That sounds really attractive, unless at the end of the 15 years, the data center is not valuable because of technology change, and so that has caused me to be cautious around data centers.”
About The Author