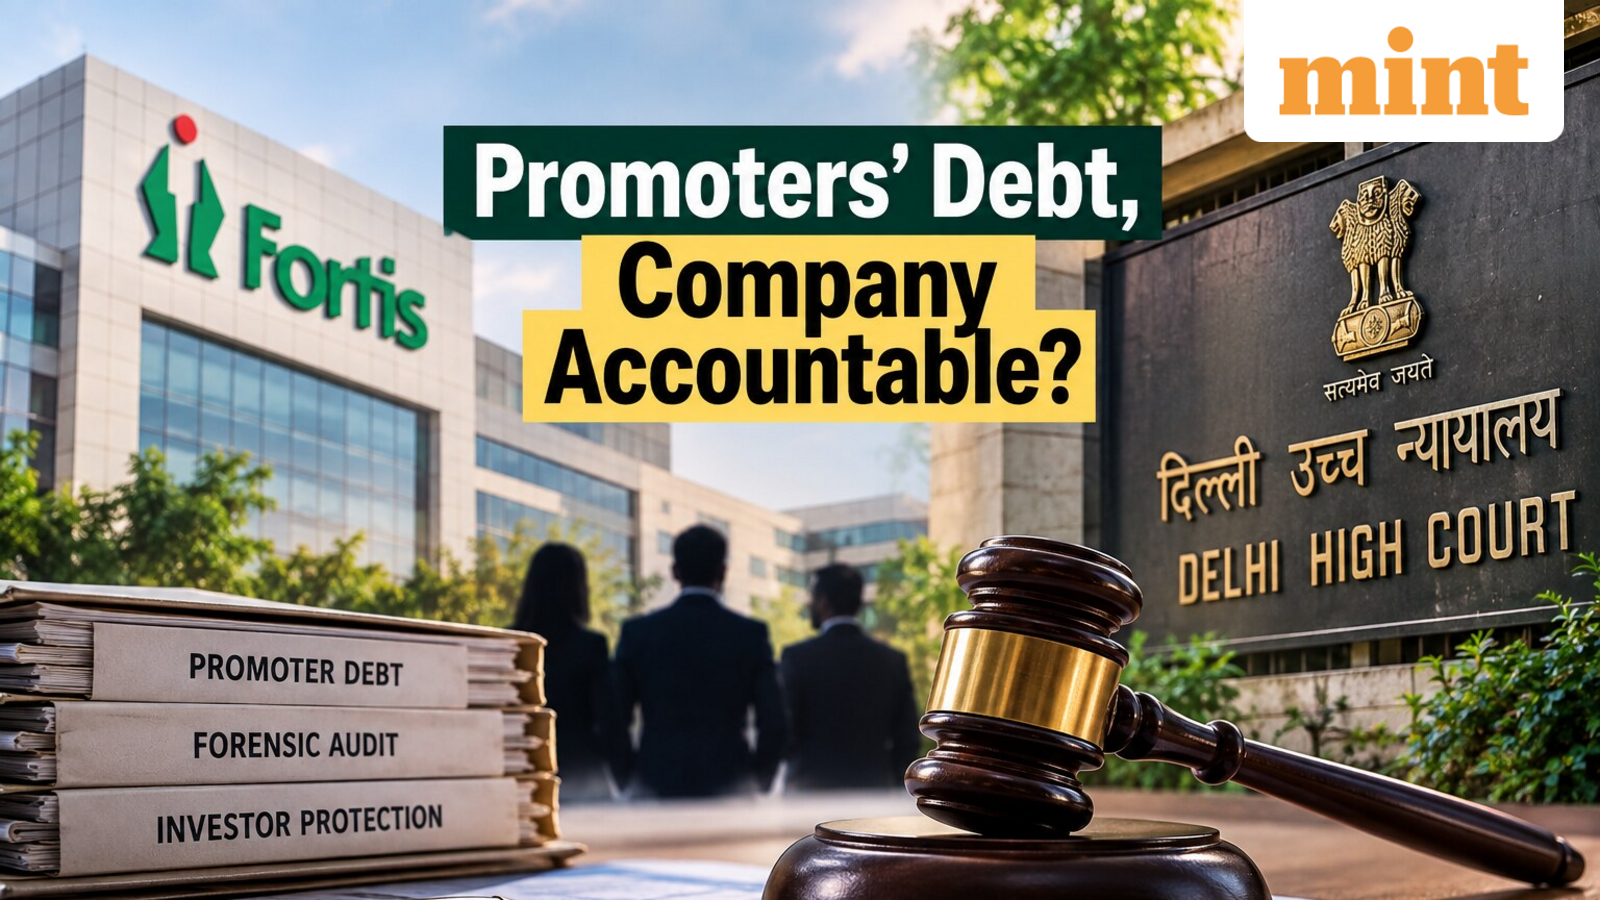
The Delhi High Court’s recent order involving Fortis Healthcare has brought a wider corporate governance question into focus: where should the liability of a listed company end when disputes arise from the personal obligations of its former promoters?
The court has ordered a forensic audit into transactions involving Fortis, while making clear that the exercise itself does not impose liability or establish wrongdoing. The audit was ordered on 31 August 2026 in proceedings to enforce a Singapore arbitration award that
Daiichi Sankyo holds against the Singh brothers, the former promoters of Fortis, in their personal capacity. The court has said the audit is fact-finding and imposes no liability, with the matter listed next on 1 April 2027.
However, the order has raised concerns about the extent to which a listed company, its current management and public shareholders can be drawn into enforcement proceedings linked to historical promoter conduct. InGovern has highlighted these concerns in its latest corporate governance alert.
Safeguarding investor interest
The Proxy advisory firm InGovern has stated in a report that the reasoning underlying the Delhi High Court’s forensic audit of Fortis Healthcare, if upheld, could expose any listed company in India to enforcement proceedings arising from the personal debts of its promoters.
The arbitration award at the centre of the dispute was against the Singh Brothers in their personal capacity, while Fortis was not a party to the arbitration, award or enforcement proceedings, according to InGovern.
InGovern said the order “effectively treats Fortis and the Singh Brothers as one and the same, while simultaneously insisting that it has not ‘pierced the corporate veil’,” a stance InGoven argued sits uneasily with settled Supreme Court jurisprudence.
InGovern’s concern is with the precedent the order’s logic could set. “If the reasoning is upheld, any listed company in India could potentially be pulled into enforcement proceedings arising from the personal liabilities of its owners.
Think about what that means in practice: board members and compliance officers could be expected to monitor and enforce the personal undertakings and liabilities of promoter-shareholders — a responsibility that no existing Indian law or regulation imposes on them,” it added.
However, InGovern stressed that the audit is a fact-finding exercise that does not by itself establish wrongdoing or liability, and that the proceedings remain sub judice. The remedy, it argued, lies with institutions rather than the courts, and it urged SEBI, the Ministry of Corporate Affairs (MCA) and, if required, Parliament to set clear thresholds for when a listed company that was not a party to a dispute may be drawn into execution proceedings against its former promoters.
At the same time, InGovern said stronger investor protection should not weaken legitimate enforcement against actual judgment debtors. The objective, it argued, should be to ensure that assets wrongfully dissipated by those liable can still be traced and recovered, while protecting bona fide acquirers, public shareholders and successor management from open-ended exposure.
InGovern has proposed that SEBI, the Ministry of Corporate Affairs and, if required, Parliament establish clearer rules on the finality of cleared control transactions. It also suggested that listed companies should not be drawn into enforcement proceedings against former promoters merely because their shares or corporate assets are connected to a dispute, unless there is a demonstrable prima facie basis that the company knowingly participated in the alleged dissipation or diversion of assets.
Why the Fortis order matters for shareholders
For public shareholders, however, an investigation can itself have consequences. InGovern pointed out that Fortis has a large public shareholding and that the audit can create disclosure requirements, management and legal costs and reputational overhang even before any liability is established.
The broader issue, according to InGovern, is whether investors and acquirers can treat a regulator-cleared change in control as final. The report said India’s approval framework provides mechanisms for board and shareholder approval, competition clearance, stock-exchange disclosures and compliance with the SEBI Takeover Regulations, but does not clearly specify the legal finality attached to such transactions.
It further added that the concern for investors is that a listed company could potentially face scrutiny because of obligations connected to former promoters, even when the company itself was not party to the underlying dispute.
“If the reasoning is upheld, any listed company in India could potentially be pulled into enforcement proceedings arising from the personal liabilities of its owners. Think about what that means in practice: board members and compliance officers could be expected to monitor and enforce the personal undertakings and liabilities of promoter-shareholders.”
InGovern also highlighted the potential impact on foreign investors. IHH had invested around ₹4,000 crore into Fortis after a competitive bidding process involving multiple global investors, with the transaction subsequently going through SEBI’s takeover process and receiving statutory approvals.
InGovern concluded that the Fortis matter exposes a broader gap in India’s corporate governance framework: while enforcement against judgment debtors must remain effective, investors and listed companies also require predictable boundaries around historical promoter liabilities.
It further stated that prolonged uncertainty could raise the cost of capital and discourage long-term investors from acquiring and rehabilitating stressed listed companies.
Disclaimer: The views and recommendations made above are those of individual analysts or broking companies, and not of Mint. We advise investors to check with certified experts before making any investment decisions.
About The Author