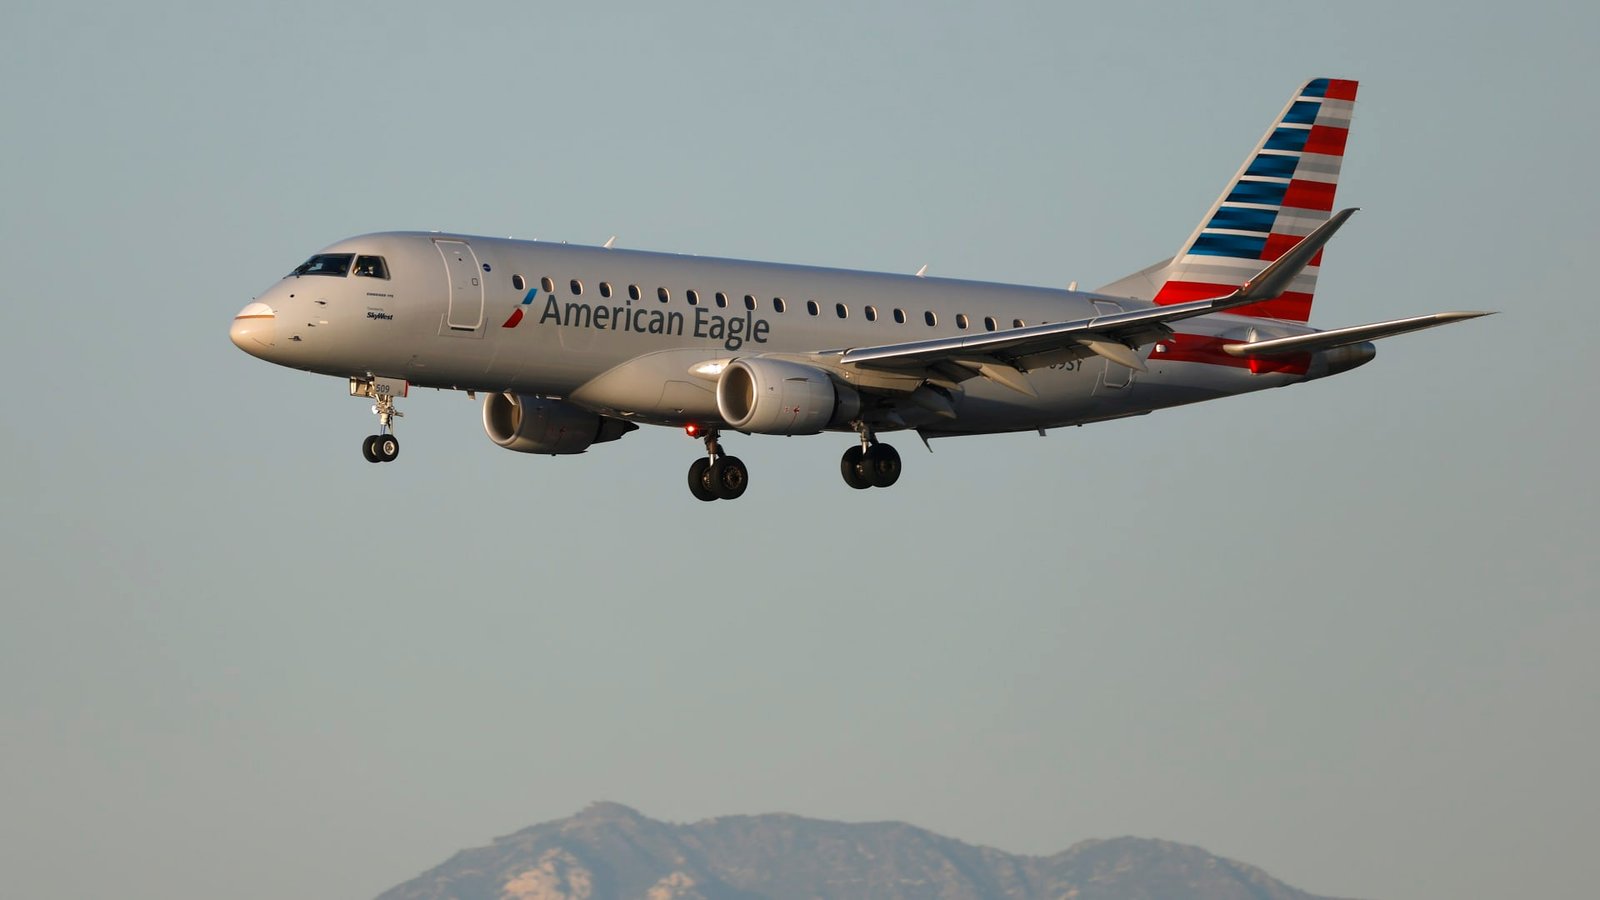
American Airlines Group is likely to gain ground despite high fuel costs, thanks to increased passenger fares and investment in key travel hubs, according to Rothschild & Co. Redburn. The investment bank upgraded American Air to buy from neutral with a $17.50 price target, implying nearly 24% upside from Monday’s close. “We have found it increasingly difficult to justify a Neutral rating on American,” analyst Gavin Tennant said Tuesday in a note to clients. “Its re-established network and investments in key hubs, coupled with a high-fare growth environment, provide room to expand revenues, return to delevering the balance sheet and generate sustainable margin expansion in outer years.” Shares of American Air have shed nearly 8% year to date in the face of higher jet fuel costs due to the Iran war, pressuring profit margins and leading increased fares. American has also reduced the size of its fleet and curtailed service at some airports in a bid to cut costs and streamline operations. The stock is 11% higher in the past month. AAL YTD mountain American is down 8% year to date but 11% higher in the past month American is likely to benefit from prior fare hikes if fuel costs begin to moderate, Rothschild said. “Robust U.S. travel demand, rational capacity growth and fuel cost volatility should keep fares elevated through 2027,” Tennant wrote. “We expect airlines will hold onto higher pricing points if jet fuel costs recede, providing a tailwind to margin expansion.” Moreover, the stock is relatively inexpensive, offering an “attractive entry point for an improving business.” Analysts on Wall Street are split on American Airlines. Of 26 analysts, only 12 rate American buy or strong buy, while 13 call it no more than a hold, LSEG data shows.