This drug wholesaler's transformation is paying off. Here's why the stock still looks attractive
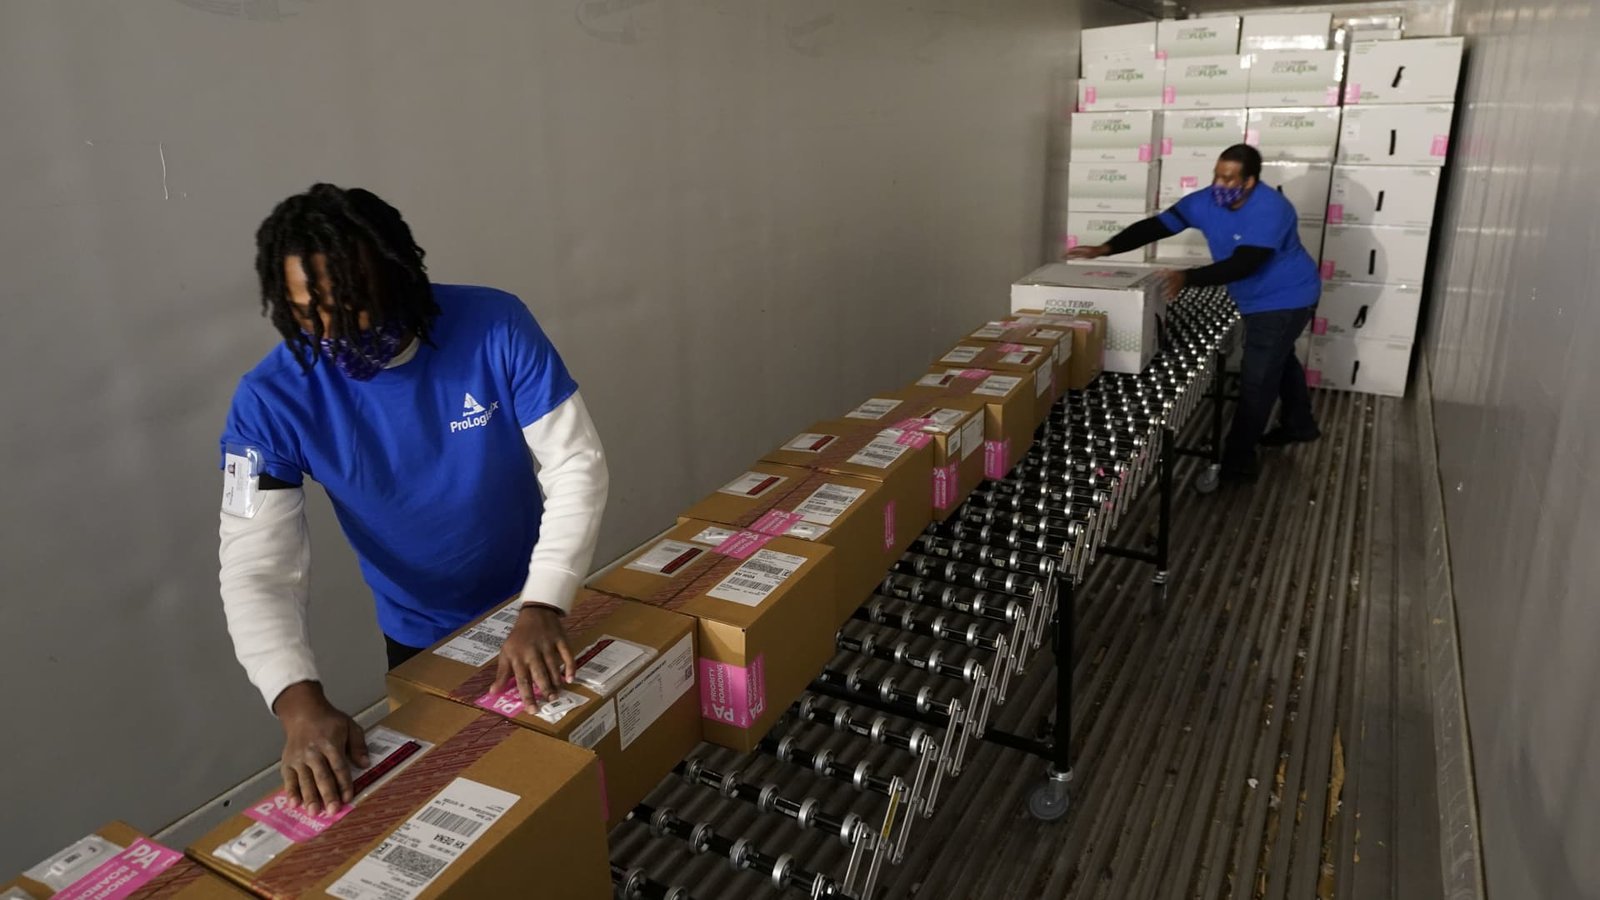
McKesson’s earnings mix is improving. Its oncology and technology units are generating higher margins and growing faster than McKesson’s traditional wholesale business. Portfolio changes are accelerating the shift. McKesson has completed the Precision Medicine Group acquisition, agreed to invest in Option Care Health and is preparing to separate Medical-Surgical Solutions. Despite a substantial rally, McKesson’s valuation leaves room for upside as management raises earnings expectations, expands its specialty care platform, and formalizes its extended distribution agreement with CVS Health. After all the recent market volatility, investors looking for less drama may want to consider McKesson . The drug distributor has outperformed the market in 2026 with a more than 30% climb, but it’s still at a significant discount to its five-year median multiple as management keeps raising the bar on earnings. The company is evolving into a broader healthcare services and technology company with its expansion into more lucrative areas such as oncology, biopharma services, infusion therapy, and medical technology. The power of this shift, which is still underway, should provide the stock with momentum. McKesson’s second-quarter results on Nov. 4 provided important confirmation of this investment thesis. Fiscal 2027 adjusted earnings guidance was raised to a range of $45.60 to $46.40 per share from $44.20 to $45.00, reflecting continued strength across the portfolio and implying growth of 17% to 19%. It also demonstrated how it is leveraging its higher-margin operations to boost the bottom line. Though its oncology and technology businesses accounted for approximately 15% of second-quarter revenue, the units generated nearly 37% of adjusted segment operating profit. The push into higher-growth specialty care will become more pronounced as McKesson further reshapes its portfolio. The company completed the acquisition of Precision Medicine Group , a provider of clinical research and commercialization services, on Nov. 2. On Oct. 6, alongside private-equity firm Clayton, Dubilier & Rice, McKesson agreed to invest $1.4 billion for a 49% stake in Option Care Health, the nation’s largest independent provider of home and alternate-site infusion services. The deal values Option Care at roughly $5.8 billion and is expected to close in the first half of 2027. During the latest earnings call, CEO Brian Tyler said McKesson likes “the future trajectory of community and home-based care” and views the Option Care investment as a way of incubating future growth platforms alongside its existing specialty strategy. Another catalyst is the planned separation of McKesson Medical-Surgical. The supplier of physician offices and nursing homes will be renamed Wellverse in February, and an initial public offering is expected in the second half of 2027. McKesson also has announced an agreement in principle to extend its pharmaceutical distribution partnership with CVS Health through June 2032. Once the deal is completed, it will provide longer-term visibility into a key customer relationship and remove a potential overhang on the stock. Investors should now focus on whether the company can sustain its momentum through the second half, particularly as it accelerates investment in its core distribution capabilities and specialty businesses. McKesson’s evolution The largest of America’s three big drug wholesalers, McKesson has long been known for buying medicines from manufacturers and distributing them to pharmacies, hospitals and clinics on razor-thin spreads, with higher-margin services layered on top. It serves retail chains such as CVS, independent pharmacies, health systems and physician groups, and competes mainly with Cencora and Cardinal Health . Its operations are overwhelmingly in the U.S., but it has a Canadian wholesale arm. The improving mix is the story, and the second-quarter results demonstrated that earnings growth is broadening across the portfolio. North American pharmaceutical, McKesson’s legacy wholesale business, generated the lion’s share of second-quarter revenue, 82.3%, but approximately 52% of adjusted segment operating profit. Its margin of 1.14% rose 16 basis points year over year due to better operating leverage. Oncology & multispecialty, which supports community cancer practices, contributed 13.5% of McKesson’s revenue, but 21.4% of adjusted segment operating profit, at a 2.85% margin. The unit’s operating profit rose 8%, but excluding $51 million of net gains in the prior-year quarter, underlying profit growth was a much stronger 23%. Prescription technology solutions, which helps drugmakers get patients onto therapy, accounted for only 1.4% of revenue but 15.4% of adjusted segment operating profit, due to its much higher 20.2% margin. The unit delivered solid results, with operating profit up 18% from the prior year and margins expanding 123 basis points. Growth factors Demand is driven by an aging population, rising prescription volumes and a drug pipeline tilted toward specialty medicines that are costly, complex to handle and increasingly dispensed outside hospitals. These trends favor McKesson’s evolving mix. More often, cancer care is moving into community settings, drugmakers are outsourcing the patient-access work, and providers are leaning on a few scaled partners for supply security. Factors such as a national distribution network, licensing and controlled-substance compliance create barriers to entry, which is why only three wholesalers move most of the nation’s drugs. However, McKesson has more aggressively embraced oncology and biopharma services than its rivals. “When you parlay strong, healthy, broad-based growth with continued operational excellence and productivity within our supply chain ecosystem, we saw really nice operating leverage, close to 150 basis points,” CFO Kenny Cheung said, citing broad-based growth in prescription volumes, specialty products and GLP-1s for the strength. The medical-surgical business remained the exception. Adjusted operating profit fell 10%, although revenue increased 5%. Management expects segment profit to range from a 4% decline to flat for the full year, reinforcing the rationale for the planned spinoff. Meanwhile, cash generation is also strong. McKesson reported about $2.9 billion in free cash flow during the second quarter, bringing first-half free cash flow to $2.6 billion, up 131% year over year despite a seasonally negative first quarter. The company expects $4.5 billion to $4.9 billion in free cash flow for the full fiscal 2027. Capital returns also support per-share growth. The company repurchased about $3.4 billion of stock during the first half and expects $5 billion in buybacks for the full fiscal year. A 15% dividend increase approved in the first quarter adds to the shareholder-return story. McKesson’s valuation As of Thursday’s close, McKesson trades at about 23 times the midpoint of fiscal 2027 adjusted EPS guidance of $45.60 to $46.40. That’s still below the roughly 25.3 times five-year historical median. MCK YTD mountain McKesson performance year to date Is the historic median appropriate? Arguably, the new McKesson is a more dynamic and faster-growing company, arguing for an even higher multiple. On the other hand, interest rates have increased, which argues for a lower multiple. Call the opposing forces a wash. Given the stock’s substantial rally since early June, the valuation cushion has narrowed, but continued earnings growth would support further multiple expansion. McKesson’s premium valuation relative to Cardinal Health also leaves less room for execution missteps. Free cash flow guidance implies a yield of about 3.8% at a market capitalization of roughly $124.35 billion. Applying a 25.3 times multiple to consensus calendar 2027 EPS of $50.53 produces a price target of approximately $1,278, or about 19% above Thursday’s close. Earnings guidance increases will be key for future appreciation. McKesson could get some help from Precision Medicine Group, which is expected to add 10 cents to 20 cents per share to earnings this year and $1.60 to $1.80 by year three. The expected closing of the Option Care deal in early 2027, the planned Wellverse IPO, and finalizing the extended CVS contract through 2032 should further advance the company’s strategy. Meanwhile, stock buybacks and investments in artificial intelligence, automation and productivity could provide additional support for earnings growth. On the other hand, regulatory risk is real as reforms to the 340B program or Medicare Part D economics could pressure distributor margins. CVS is the largest customer, and its extension is not yet definitive. Opioid-related liabilities remain, and execution risk surrounds its portfolio changes. GLP-1 drugs remain an important source of distribution volume, but the business is exposed to changes in pricing, payer coverage and distribution channels, while generating relatively thin margins. Management said GLP-1 demand is beginning to normalize following initial strong uptake in the Medicare Bridge Program. Conclusion McKesson is a better business than its wholesaler label suggests. Growing oncology, infusion and technology operations are improving earnings quality, while substantial share repurchases amplify per-share growth. With an improving outlook and the stock still trading below its historical valuation multiple, I believe the market continues to underestimate McKesson’s earnings power and the durability of its transformation. THIS CONTENT IS PROVIDED FOR INFORMATIONAL PURPOSES ONLY AND DOES NOT CONSTITUTE FINANCIAL, INVESTMENT, TAX OR LEGAL ADVICE OR A RECOMMENDATION TO BUY ANY SECURITY OR OTHER FINANCIAL ASSET. THE CONTENT IS GENERAL IN NATURE AND DOES NOT REFLECT ANY INDIVIDUAL’S UNIQUE PERSONAL CIRCUMSTANCES. THE ABOVE CONTENT MIGHT NOT BE SUITABLE FOR YOUR PARTICULAR CIRCUMSTANCES. BEFORE MAKING ANY FINANCIAL DECISIONS, YOU SHOULD STRONGLY CONSIDER SEEKING ADVICE FROM YOUR OWN FINANCIAL OR INVESTMENT ADVISOR. Click here for the full disclaimer.