(WO) – Harbour Energy averaged a record 501,000 boed over the first nine months of the year, up 6 percent from a year earlier, and lifted full-year production guidance to 500,000-505,000 boed from 490,000-500,000 boed on strong operational performance and the integration of LLOG in the U.S. and Waldorf in the UK.
Third-quarter production was 484,000 boed, up 9 percent year on year. Output for the period was split broadly 40 percent liquids, 40 percent European gas and 20 percent other gas. The LLOG addition in the U.S. from February and Waldorf in the UK from July more than offset divestments in Indonesia and Vietnam and UK natural decline. October production, affected by later maintenance programs and Hurricane Isaias in the U.S., averaged 511,000 boed.
Norway was the largest contributor at 177,000 boed for the nine months, followed by the UK at 142,000 boed, Argentina at 74,000 boed and the U.S. at 35,000 boed. Norway output rose on strong reliability at key hubs, infill drilling at Njord and the start-up of the Skarv satellites in August, a year ahead of schedule. New wells came online in Argentina and in the U.S., where initial rates from the latest Who Dat and Buckskin wells were better than expected.
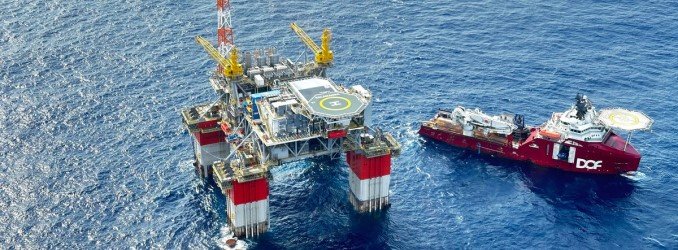
In the U.S. Gulf, a second drilling rig arrived in September to accelerate high-return investment opportunities. Who Dat East was approved in August, and the Salamanca FPS subsea pump project is on track for final investment decision (FID) by year-end. Harbour was awarded 12 leases, eight as operator, in the Big Beautiful Gulf 3 lease sale, and now expects to spud the Kingsroad exploration well around year-end.
In Norway, Gjøa North and Ofelia were sanctioned in the second quarter, and five further projects are targeted to reach FID by year-end, with the potential to deliver 100 percent Norway reserves replacement. The Omega Sør discovery is being fast-tracked toward a potential FID by year-end, and the EZZ-2 exploration well in Egypt was tied into existing infrastructure and began production in the third quarter.
In Mexico, an MOU was signed for the Lakam Ha FPSO at Zama, and invitations to tender for major FEED packages were issued. Harbour continues to target FID-readiness for the Zama and Kan projects, both Harbour-operated, around year-end 2027. In Argentina’s Vaca Muerta, three gas wells were drilled on the Aguada Pichana Este licence during the quarter, with nine wells connected during the period.
Unit operating costs were $13.9/boe, compared with $12.8/boe a year earlier, and full-year guidance of about $14.5/boe was reiterated. Total capex guidance is unchanged at $2.2 billion to $2.4 billion, weighted to the fourth quarter by the second U.S. rig and the Waldorf assets. Harbour raised its 2026 free cash flow outlook by $800 million to about $2.6 billion and announced a further $150 million share buyback.
About The Author